The Freshest Washington DC Data.
The DC real estate market is constantly evolving. Stay ahead of trends and shifts with weekly and monthly data and summaries.
Comprehensive. Detailed. Understandable.
District of Columbia Weekly Market Data
DC City Weekly Data
| BRIGHT MLS DATASET | WEEK ENDING OCT. 4 | PRIOR YEAR | PRIOR WEEK |
|---|---|---|---|
| WEEKLY SHOWINGS | 2,141 | 2,377 | 1,964 |
| NEW SALES CONTRACTS | 118 | 135 | 147 |
| MEDIAN DAYS TO CONTRACT | 50 days | 43 days | 35 days |
| NEW LISTINGS | 251 | 274 | 289 |
| MEDIAN LIST PRICE | $735,000 | 698,750 | 649,000 |
| ACTIVE LISTINGS | 2,920 | 2,927 | 2,953 |
| % ACTIVE WITH PRICE DROP | 8.1% | 7.3% | 7.1% |
| CANCELED LISTINGS | 40 | 45 | 38 |
Washington DC Metro Area Weekly Data
The DC Metro Area market consists of District of Columbia, Arlington Va, Alexandria Va, Alexandria City Va, Fairfax County, Fairfax City, Falls Church, Montgomery County Md, Loudoun County Md, and Frederick County Md.
| BRIGHT MLS DATASET | WEEK ENDING OCT. 4 | PRIOR YEAR | PRIOR WEEK |
|---|---|---|---|
| WEEKLY SHOWINGS | 14,794 | -14.2% | +2.1% |
| NEW SALES CONTRACTS | 893 | -19.5% | -5.7% |
| MEDIAN DAYS TO CONTRACT | 36 days | +6 days | +2 days |
| NEW LISTINGS | 1,412 | -1.3% | -1.5% |
| MEDIAN LIST PRICE | $625,000 | +2.5% | +1.6% |
| ACTIVE LISTINGS | 12,525 | +19.6% | -0.1% |
| % ACTIVE WITH PRICE DROP | 10.4% | +0.2 pp | +0.2 pp |
| CANCELLED LISTINGS | 199 | +48.5% | +15.0% |
Buyer activity across the DC Metro remained weak during the week ending October 4th. New contracts fell 5.7% from the previous week and were 19.5% below the same week last year. Showings improved 2.1% week over week, but remained 14.2% below last year’s level. Homes also stayed on market longer, with the median time from listing to contract pushing up to 36 days, six days longer than a year ago.
Inventory remains substantially higher than last year. Active listings totaled 12,525, nearly unchanged from the prior week but 19.6% above 2025. New listings were down slightly both year over year and week over week, suggesting that the elevated inventory is being sustained less by a surge of new sellers than by homes already on the market taking longer to sell.
Seller withdrawals are also becoming more noticeable. Canceled listings rose 15.0% in a single week and were 48.5% higher than a year ago. With contracts down sharply from last year while inventory remains elevated, some sellers appear to be choosing to leave the market rather than continue waiting for a buyer.
DC (City) Monthly Data
SEPT 2026
Oct. 2026 data will be released Nov. 11, 2026
| BRIGHT MLS DATASET | SEPTEMBER 2026 | PRIOR YEAR | PRIOR MONTH |
|---|---|---|---|
| TOTAL SOLD DOLLAR VOL | $351,984,861 | -3.0% | -24.3% |
| AVG SOLD PRICE | $870,012 | +3.6% | -17.2% |
| MEDIAN SOLD PRICE | $660,000 | -2.9% | -3.2% |
| UNITS SOLD | 398 | -6.8% | -9.1% |
| AVG DAYS ON MARKET | 46 | -2.1% | -9.8% |
| AVG SP TO OLP | 95.7% | +0.3 pp | 0.0 pp |
| ACTIVE LISTINGS | 3,041 | +1.1% | +21.0% |
| NEW LISTINGS | 1,067 | -6.9% | +86.9% |
| NEW PENDINGS | 499 | -9.3% | +33.8% |
| ALL PENDINGS | 603 | -9.5% | +8.3% |
Source: SmartCharts Pro / Bright MLS. September data calculated October 8, 2026. Prior Year compares with September 2025; Prior Month compares with August 2026. pp = percentage points. SP = sold price; OLP = original list price.
September 2026 DC City Summary
Washington DC entered the fall market with a seasonal rebound in listings and new contracts from August, but activity remained below last September. New listings rose 86.9% month over month to 1,067, while new pending contracts increased 33.8% to 499. Compared with September 2025, however, new listings were down 6.9% and new contracts were down 9.3%.
Closed sales totaled 398, down 6.8% from a year earlier and 9.1% from August. The median sold price fell 2.9% year over year to $660,000, while the average sold price increased 3.6% to $870,012. Those measures describe different aspects of the properties that sold; a higher average alongside a lower median doesn’t establish broad price appreciation.
Active inventory increased 21.0% from August to 3,041 listings, finishing 1.1% above September 2025. Homes that sold spent an average of 46 days on market, one day fewer than last September, and sellers received an average 95.7% of their original asking price. With new contracts below last year’s pace and more listings arriving after August, buyers had a larger selection heading into October.
DC City Year to Date Summary January Through September
Through September, Washington DC recorded 4,700 closed sales, down 3.9% from 4,892 during the same period in 2025. New pending contracts declined 2.8%, while new listings fell 7.3%. The median sold price was essentially unchanged at $670,500, compared with $670,000 a year earlier, but homes that sold spent an average of 50 days on market, up from 46.
The property-type breakdown shows a much less uniform market. Detached sales increased 10.1% to 819 and detached new contracts rose 8.6%. Townhouse sales were nearly flat, down 0.5% to 1,901, while new contracts increased 2.4%. Condo and co-op sales fell 11.6% to 1,974, and new contracts declined 11.2%.
Prices alone don’t capture those differences in demand. The year-to-date median sold price declined 1.2% for detached homes and 2.2% for townhouses, while the condo and co-op median edged up 0.2% to $490,000. That nearly unchanged condo median describes the units that successfully sold, even as substantially fewer sales and contracts were completed.
September 2026 Property Type Summary
Detached homes recorded 85 September closings, up 46.6% from 58 a year earlier, while new contracts increased 4.6% to 91. The median sold price fell 16.5% to $1,064,500. That monthly price decline accompanies a small sales sample and a changing mix of homes sold, so it shouldn’t be read as a comparable decline in the value of every detached home.
Townhouses recorded 159 closings, down 13.6% from September 2025, and a median sold price of $795,000, down 5.4%. New contracts were nearly unchanged from a year earlier at 219. September ended with 921 active townhouse listings and a contract ratio of 0.30 pending contracts per active listing.
Condos and co-ops remained the weakest segment by contract activity relative to available inventory. September closings fell 16.3% to 154 and new contracts declined 22.0% to 188, even as the median sold price rose 2.1% to $499,950. Active inventory increased 7.3% from a year earlier to 1,737 listings, accounting for 57.1% of the city’s total active inventory.
The condo and co-op contract ratio was 0.12 pending contracts per active listing, compared with 0.18 last September and a five-year September average of 0.23. Sold units averaged 51 days on market, down from 59 a year earlier, but that faster pace among completed sales didn’t translate into stronger overall contract activity. Prices and selling times for successful transactions tell only part of the story.
DC Metro Area Monthly Data
| BRIGHT MLS DATASET | SEPTEMBER 2026 | PRIOR YEAR | PRIOR MONTH |
|---|---|---|---|
| TOTAL SOLD DOLLAR VOL | $3,448,655,200 | -7.3% | -13.2% |
| AVG SOLD PRICE | $698,622 | +0.2% | -4.5% |
| MEDIAN SOLD PRICE | $569,000 | -0.2% | -4.8% |
| UNITS SOLD | 4,903 | -7.4% | -9.3% |
| AVG DAYS ON MARKET | 33 | +3.1% | +6.5% |
| AVG SP TO OLP | 97.6% | -0.2 pp | -0.6 pp |
| ACTIVE LISTINGS | 17,704 | +21.4% | +15.2% |
| NEW LISTINGS | 7,412 | +1.2% | +24.0% |
| NEW PENDINGS | 4,886 | -16.7% | -6.2% |
| ALL PENDINGS | 6,099 | -14.0% | -7.1% |
Source: SmartCharts Pro / Bright MLS. September data calculated October 8, 2026. Prior Year compares with September 2025; Prior Month compares with August 2026. pp = percentage points. SP = sold price; OLP = original list price.
September 2026 DC Metro Summary
The DC Metro market saw its listing count rise considerably in September, while new buyer commitments weakened.
New listings rose 24.0% from August to 7,412, but new pending contracts fell 6.2% to 4,886; 16.7% below September 2025 levels.
Closings totaled 4,903, down 7.4% from a year ago. Active inventory increased 15.2% from August to 17,704 listings, leaving buyers with 21.4% more available inventory than last September.
Five-year September comparisons show an imbalance that extends beyond the usual seasonal changes. New listings were just 0.9% above their September average, but new contracts were 12.9% below average and closings were down 7.8%.
Inventory was a whopping 41.9% higher than the five-year September average of 12,475.
Sold homes averaged 33 days on market compared with the September norm of 27. Median sold price remained comparatively stable at $569,000, down 0.2% from a year earlier and 4.8% from August, but 4.5% above its five-year September average of $544,300. The more pronounced weakness was in contract activity relative to available inventory.
The year-to-date picture was stronger than September’s monthly reading. Through September, regional closings increased 1.6% to 51,231, new contracts edged up 0.3% to 52,790, and the median sold price rose 1.7% to $595,000. New listings increased 3.0%, outpacing the growth in contracts and closings. The region was still ahead of 2025 on those cumulative transaction measures, while September’s smaller contract pipeline and larger inventory pointed to softer conditions heading into October.
Source: September 2026 Greater DC Area Market Statistics and Local Market Insight reports, SmartCharts Pro / MarketStats by ShowingTime, Bright MLS. Data calculated October 8, 2026. Five-year averages compare September readings; YTD compares January through September in both years.
DC CONDOS + CO-OPS
Median sold price
$499,950
September 2026
−7.4% from August · +2.1% year over year
October 2025–September 2026
Exact September price; historical bars approximate.
DC CONDOS + CO-OPS
Months of supply
8.2 months
September 2026
Approximate chart reading
October 2025–September 2026
Chart readings approximate.
DC CONDOS + CO-OPS
Median days on market
43 days
September 2026
Approximate chart reading
October 2025–September 2026
Chart readings approximate.
Source: SmartCharts Pro / Bright MLS, October 8, 2026. Approximate chart readings are marked with ≈. Median days on market is a different measure from average days on market.
DC’s Condo Market Remains Its Weakest Segment
One of the biggest stories of the past two years has been the persistent weakness of the District’s condominium market. Condominiums and co-ops remain the weakest major property segment by contract activity relative to available inventory. September ended with 1,737 active listings, accounting for 57.1% of the city’s inventory, while condos and co-ops supplied only 38.7% of the month’s closings.
That weakness isn’t always apparent in reported prices. Through September, 1,974 condos and co-ops had sold in 2026, down 11.6% from 2,232 during the same period last year. New pending contracts declined 11.2%, yet the median sold price edged up 0.2% to $490,000. The prices recorded by a relatively small percentage of successful sales don’t reflect significant inventory increases, slowing sales pace and other market indicators provide a full picture of the market.
Prices, Supply and Selling Times Tell Different Stories
These 5-year charts show how those measures can move in different directions. September’s median sold price was $499,950, up 2.1% from a year earlier but down 7.4% from August. Months of supply increased from 6.83 in August to 8.19 in September, while median days on market fell from 58 to 43.
The units that sold moved faster, even as available supply grew relative to the sales pace. A shorter selling time among completed transactions doesn’t establish that the larger pool of available condos became easier to sell. The price and selling-time figures describe successful transactions; months of supply helps put those transactions in the context of the inventory still on the market.
That is the true picture of DC’s condo market. Pricing for units sold looks healthy. But few units are selling relative to supply, so that picture is deceiving.
Condos are highly reactive to market and economic conditions and often show changes in buyer demand earlier than other housing types. The District’s condominium market was beginning to recover from the severe demand disruption of the pandemic when DC’s economic trajectory changed again in early 2025. Federal employment and spending uncertainty added another challenge to a market already contending with high mortgage rates and rising ownership costs. Since then, tighter condominium financing and insurance requirements have added further pressure to the buyer pipeline.
At the close of September 2026, the 30-year mortgage interest rate had risen to 7.58% [MND]. Key drivers are spiking 10-year Treasury yields (near 10 year highs), global bond market sell-offs, persistent inflation (at 3.4% for the 12 months ending in August 2026), increased federal government deficits, the Iran war, and the expectation of at least one more 25-basis-point rate hike by the Fed before the end of 2026.
Declining Values
So why haven’t condo prices fallen further? Part of the answer is in the math. Many condo sellers simply don’t have as much room to cut their prices. Condominiums tend to have thinner equity margins than more expensive property types, particularly when the owners purchased recently or financed with relatively small down payments.
Unlike detached homeowners who often:
- Bought years ago
- Accumulated significant appreciation
- Paid down principal
- Have flexibility to negotiate;
many condo owners:
- Purchased more recently
- Put 3–10% down
- Paid peak-pandemic prices (this is the part where you care more about what you paid for your condo than what you pay per month)
- Financed mortgage insurance
- Paid premiums on new construction
- Experienced little or no appreciation and in many cases loss
- Continue paying rising HOA dues, insurance and utility costs.
Their margins are erased, or even negative.
When prices soften, it doesn’t matter a great deal to those with 40% equity, but it is a sale-killer for others. And as inventory levels continue to rise, prices continue to lower, widening the gap between what’s owed and current market value. Even modest price declines can make it difficult to sell without bringing cash to closing, leaving some owners effectively trapped in their homes.
Washington’s condominium market has historically depended on two primary buyer groups:
The first is first-time homebuyers. Condominiums have long served as the entry point into homeownership for young professionals beginning careers in government, law, consulting, lobbying, nonprofits, healthcare, and related industries. These buyers traditionally purchase a condominium as their first home before moving up to a rowhouse or detached property;
The second is part-time or pied-à-terre buyers. Members of Congress, federal executives, diplomats, attorneys, corporate executives and other professionals have historically purchased condominiums because they wanted a low-maintenance residence close to Capitol Hill, downtown, or federal agencies. They weren’t necessarily looking for the least expensive housing, they were buying convenience, security and a lock-and-leave lifestyle.
Both groups have backed off.
Certainly the first-time buyer pool shrank because affordability deteriorated, mortgage interest rates rose, and cratering federal employment caused many younger households to search elsewhere. But also, the city’s overall desirability has suffered over the past two years. According to the D.C. Policy Center, domestic out-migration increased to 6.0 per 1,000 residents (up from 0.6) and international migration declined to 5.7 per 1,000 residents (down from 9.2). Overall grew slightly by 0.3% entirely by natural increase (births minus deaths), not migration.
That’s a real problem for condominiums.
Condominiums are not just another housing type in Washington. They are the foundation of the District’s homeownership ladder. When fewer buyers enter through that first rung, fewer owners move up to larger homes, reducing liquidity throughout the entire housing market.
Unfortunately, the challenges facing condominium owners are poised to become even greater.
Beginning this summer, Fannie Mae and Freddie Mac are implementing sweeping underwriting changes that will make financing more difficult for many condominium and cooperative buildings. Higher reserve funding requirements, stricter reserve study standards, lower deductible thresholds, and the elimination of limited reviews for most projects will leave many underfunded or poorly managed associations unable to meet agency standards. Buyers may not discover that a building is non-warrantable until late in the financing process, causing transactions to fail just before closing.
At the same time, the DC Council is considering the Condominium Insurance Amendment Act of 2025 (B26-0495), legislation that would substantially increase the financial exposure of condominium owners by raising deductible pass-through limits, expanding insurance requirements, and requiring broad waivers of subrogation. Although presented as consumer protection, the proposal could shift significantly more financial risk from condominium associations onto individual owners, particularly in situations where the origin of property damage is disputed, a common occurrence in multifamily buildings.
The Council is also considering a pied-à-terre tax similar to the program now under fire in NYC. This would disproportionally affect condominiums.
Taken together, these trends suggest the District’s condominium market is no longer facing a temporary cyclical slowdown, it’s undergoing a structural shift. A smaller pipeline of first-time and part-time buyers, rising ownership costs, tighter financing standards and additional legislative uncertainty are all reducing the buyer pool. Until that buyer pipeline begins to expand again, condominiums are likely to remain the weakest segment of Washington’s housing market, and the first place where broader economic changes become visible.
Mortgage Rates as of October 12 2026
Mortgage rates eased in early October but remained substantially above their late-August level. Mortgage News Daily’s 30-year fixed-rate index rose from 6.75% at the end of August to 7.60% on September 30. Its latest posted reading, dated October 9, was 7.48%. That retreat offered some relief, but borrowing remained considerably more expensive than before September’s increase.
The index provides a daily benchmark based on lender rate sheets for a borrower with strong credit and a substantial down payment. It isn’t a rate available to every buyer. Actual quotes vary with the borrower, property, loan program and pricing terms, including discount points.
Sources: Mortgage News Daily rate index and methodology; October 9 rate commentary. Updated October 12, 2026; latest posted rate dated October 9.
How the Fed Affects Mortgage Rates
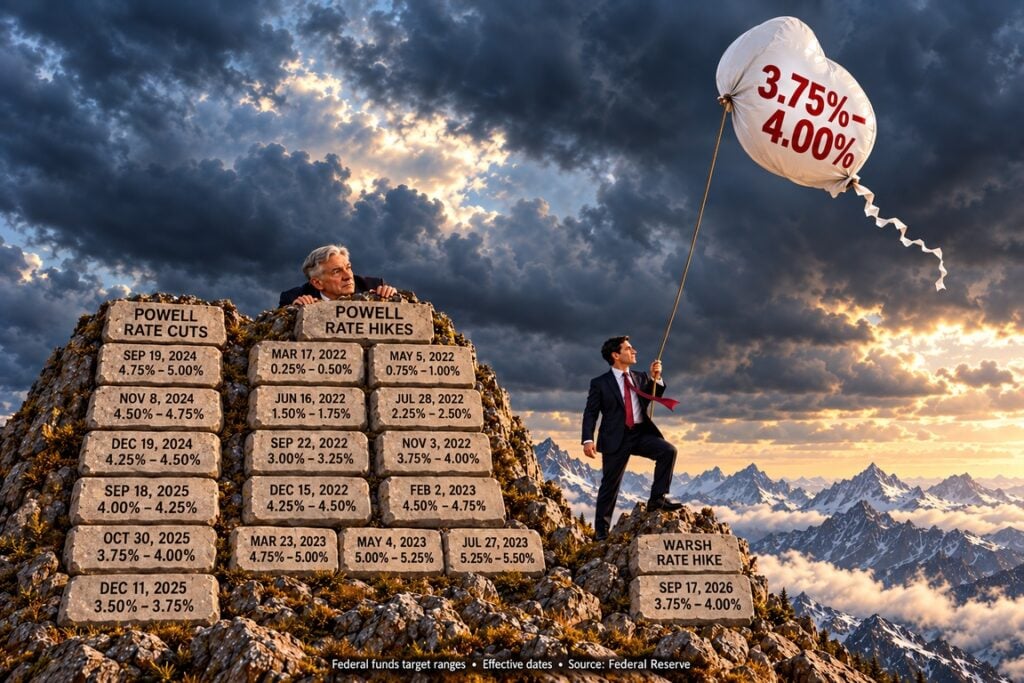
The Federal Reserve raised its federal funds target range by 25 basis points to 3.75%–4.00% on September 16. That is a short-term policy rate, rather than the rate lenders charge for a 30-year fixed mortgage. Fixed mortgage rates are more directly influenced by mortgage-backed securities, with Treasury yields providing a related bond-market benchmark. Investors’ expectations about inflation, economic growth and future Fed policy help determine those borrowing costs.
The relationship is different for variable-rate borrowing. HELOCs usually have variable rates, and their payments can change from month to month. Adjustable-rate mortgages change according to their contractual adjustment schedules, indexes and rate caps. A Fed hike doesn’t immediately reset every adjustable mortgage, and a Fed cut doesn’t guarantee an equivalent decline in fixed mortgage rates.
Sources: Federal Reserve September statement; Mortgage News Daily on mortgage bonds and Treasury yields; CFPB on HELOCs; CFPB on adjustable-rate mortgages.
What Higher Rates Mean for Buyers and Sellers
The payment difference is substantial even when the rate change is less than a percentage point. On a $500,000 mortgage amortized over 30 years, principal and interest would be approximately $3,243 a month at 6.75%, compared with $3,489 at 7.48%. That’s about $246 more each month for the same loan amount, before taxes, insurance, mortgage insurance or association fees. Buyers working within a fixed monthly budget may need to borrow less or reconsider which properties fit.
Higher rates can also discourage existing owners from selling when a move would require giving up a much cheaper mortgage. That mortgage lock-in can restrict the supply of homes for sale even as higher borrowing costs weaken buyer demand. Higher rates therefore don’t guarantee broad price declines: the result depends on the balance of available homes and buyers within each market and property type. Fewer transactions can coexist with relatively resilient sold prices. That’s something to remember as we move through the final quarter of 2026. The Fed has signaled that there may be at least one more rate hike this year and nearly half the FOMC board hints at 2 more hikes in this cycle.
Sources: Mortgage News Daily rate comparison; FHFA research on mortgage lock-in. Payment examples calculated using a fully amortizing $500,000 loan with 360 monthly payments; figures rounded to the nearest dollar.
Rates And The Housing Market
It’s not just homebuyers who are affected by higher mortgage rates.
Homeowners are also affected because borrowing costs increase overall. Home Equity Lines of Credit (HELOCs) have variable rates, as do other adjustable rate mortgages. A Fed rate hike has an immediate effect on those products.
The home building industry is also impacted. Smaller builders rely on short-term loans to build houses and higher rates means costs rise and the final project increases in price to homebuyers. An unfriendly lending environment can also deter builders altogether, slowing down the creation of new housing supply.
About The Author | Susan Isaacs
Professionally, I look for logic + upside in every situation, to the extent that it benefits my clients. I focus on market conditions supported by data, which helps make me a pricing and negotiation expert. My years of experience in this market lends perspective. My research in area and national market conditions provides a basis for market trajectory, valuable in making buying and selling projections. Above all, I am an informative and straight-forward communicator.
I represent residential real estate buyers and sellers in Washington DC and northern Virginia.