Nationally, and in the District of Columbia, condominiums are in peril. It’s time for an intervention.
Fewer owners are finding buyers. Inventory has climbed, marketing times have lengthened, and a growing number of sellers are competing for a shrinking pool of purchasers able and willing to absorb both a mortgage and the costs and risks attached to condominium ownership.
The warning is not of a district-wide price collapse, but that condo prices make the market appear more stable than underlying data would suggest.
Are Markets Hallucinating?
The national condominium market is losing transactions without losing nearly as much of its price structure. In 2025, a total of 373,000 existing condos and co-ops sold nationwide. That’s 4.6% fewer than in 2024 and the lowest annual total dating back to 2009, per NAR. Yet the national median price rose to $363,900. The national median sold price for 2026 existing condo/co-op properties is $371,600 per NAR data via YCharts. Sales are down, but median sold price is up.
Washington DC’s market is following the same general pattern, but seeing a sharper decline in sales. The District recorded 2,821 condo and co-op sales in 2025, with a median sold price slightly below $400,000. (up 3% from 2024). So far in 2026, sales are running 10.9% behind last year’s pace, while the median sold price is nearly $490,000. Sales down, sold price substantially up.
DC’s condominium market is not one market. Data differs substantially by neighborhood, price point, building, unit type and association finances. In some segments, units are selling well below prices paid three to five years ago. Owners who bought with small down payments, paid new-construction premiums or financed near the top of the market can now owe more than their units are likely to sell for after transaction costs.
Those losses are partly concealed by districtwide market data because higher-priced unit sales can bolster median data even as weaker buildings and locations lose value. Owners who can’t afford to bring cash to closing may decide not to sell, so their losses never impact closed-sales statistics. Listings that expire, withdraw or sit without a buyer disappear from the price calculation as well.
The apparent stability portrayed by general data is therefore not evidence that the condominium market is fine. It’s evidence that price statistics based only on successful sales are incomplete.
Annual totals describe the uneven market. Supply and absorption trends show how available condo inventory has risen while buyers are absorbing a smaller share of it, widening the imbalance between units offered and units sold.
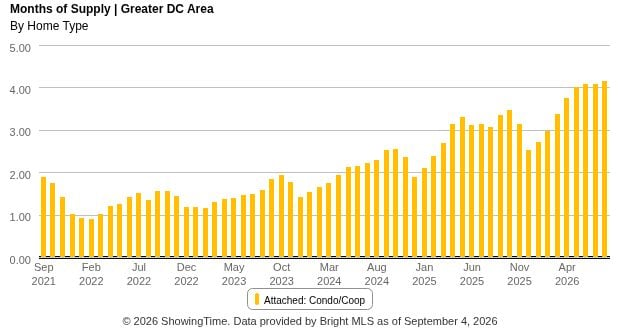
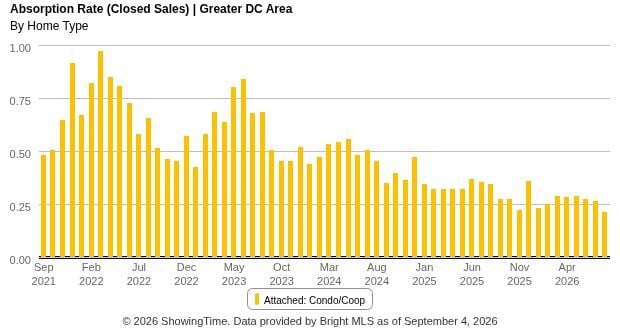
DC condo supply and absorption: More units are competing for a buyer pool absorbing a smaller share of the available inventory.
The decline is occurring not only through lower prices, but in fewer transactions, failed listings and owners who are effectively trapped in units they can’t sell without taking a loss.
Buyers are wary. Costs no longer stop at the unit’s purchase price. Buyers must consider rising association fees, soaring master-insurance policy premiums, the possibility of special assessments and the financial and physical condition of the building itself. Lenders are asking harder questions about reserves, insurance, deferred maintenance, structural problems and pending repairs. A buyer can qualify for the mortgage only to find that the condominium doesn’t.
New GSE Rules And Condo Financing
Fannie Mae and Freddie Mac, the government-sponsored enterprises, announced major revisions to their condominium project standards in March 2026. Its updated condo reserve rule [Lender Letter LL-2026-03] increases the minimum baseline reserve fund contribution for condo associations from 10% to 15% of the annual budget. The new contribution requirement applies to mortgage loan applications dated on or after January 4, 2027.
The new rules don’t order every association to replace years of missing reserves by January. For projects undergoing Full Review, the revised standard generally requires the association’s budget to allocate at least 15% of annual assessment income to replacement reserves unless the project qualifies under the reserve-study alternative. It’s not just a meaningless line item. The allocation must be funded with money collected from owners and legally set aside for replacement reserves. And that distinction is a serious concern for associations already struggling to meet the current 10% benchmark while confronting deferred maintenance and increasing operating expenses. The March announcement left associations only one budget cycle to evaluate their reserves, commission studies where necessary, determine the required contribution and collect substantially more money from owners.
An association can raise dues, impose a special assessment, borrow money, complete repairs or commission a reserve study. None can necessarily be accomplished cheaply or quickly. The cost is passed to owners, including those already trying to sell into a difficult market.
Condo associations that fail to meet the 15% threshold or provide adequate documentation become ineligible for conventional Fannie Mae-backed financing, termed “non-warrantable.” A non-warrantable condominium is one that does not meet a lender’s or secondary-market investor’s project standards. Financing may still be available, but often through fewer lenders and on less favorable terms. This can restrict buyer pool access and put downward pressure on property values.
An association can also bypass the 15% flat rule if it relies on a recently updated reserve study completed within the last three years and is actively funding its reserves at the highest recommended funding level specified by that study.
That alternative places Washington DC associations in a particularly difficult position, because unlike neighboring Maryland and Virginia, the District of Columbia doesn’t require condominium associations to commission or periodically update professional reserve studies, or to fund reserves to any specified level. DC has one of the most saturated condo markets in the country, with some of the nation’s oldest condo buildings. By omitting a recurring reserve-study requirement from the D.C. Condominium Act, Council left reserve planning to the discretion of individual boards. The consequences of that choice now extend beyond building governance. They may determine whether a buyer can obtain conventional financing and whether an existing owner can sell.
It also means that the District has no idea how many associations have current studies, how many fund study recommendations, how many meet the existing 10% benchmark or how many contribute 5% or even less. Some may be fully prepared. Others may first discover their deficiency when a buyer’s loan reaches project review and fails. Council is allowing the deadline to approach without knowing the size of the exposure, or lifting a finger to help.
Commissioning a study now doesn’t produce instant compliance, either. It costs money, takes time and may identify deferred repairs, depleted reserves or a recommended annual contribution greater than 15%. The board must then revise its budget and collect enough from owners to fund the study’s highest recommended reserve allocation.
Associations that voluntarily commissioned a qualifying study and funded its recommendations may be able to satisfy the reserve requirement through that alternative calculation. Those that did not may reach January without the document needed to use it.
The Coming Wave Of Non-Warrantables
The scale of exposure is substantial, although the failure rate is unknown. Community Associations Institute CEO Dawn Bauman has said that roughly 40% of financed condominium purchases historically relied on Limited Review. Those transactions now move into Full Review unless the project qualifies for a waiver. That does not mean 40% of condominium projects will become nonwarrantable. It means a large share of financed purchases will now require examination of project finances, reserves, insurance and building condition that the former route did not require.
National reserve-industry data indicate that underfunding is widespread, but measures of accumulated reserve adequacy cannot be converted directly into a failure rate for an annual budget-allocation test. No comparable estimate exists for DC because the District never required the information needed to calculate one. For an affected building, however, the result can be immediate: a conventional loan may fail, narrowing the buyer pool to cash purchasers or those able to obtain more expensive alternative financing.
Maryland and Virginia Have Stronger Reserve Laws
House Bill 292 introduces strict mandatory reserve funding rules that became effective October 1, 2025. The law mandates that funds budgeted for reserves must be physically deposited into the reserve account by the end of each fiscal year, and extends the initial funding attainment grace period to 5 years following the first study. It allows deviations only through approval by a two-thirds board vote in cases of proven financial hardship.
Virginia has multi-year reserve study requirements and strict disclosure rules. The state has long required associations under the Condominium Act and Property Owners’ Association Act to conduct reserve studies at least every five years and review them annually. Virginia enforces compliance through transparency and mandatory disclosures in resale certificates regarding reserve health and master insurance deductibles.
Compared to the District of Columbia
| Jurisdiction | Reserve Study Mandate | Mandated Update Schedule | Mandatory Funding Law |
|---|---|---|---|
| District of Columbia | No (Governed only by individual condo bylaws/instruments) | No | No (No statutory funding minimums) |
| Maryland | Yes (Via HB 107 / statutory acts) | Every 5 years | Yes (Must budget 100% of the study’s annual recommended amount) |
| Virginia | Yes (Via Virginia Condominium Act) | At least every 5 years | Yes (Must review and fund based on the study findings) |
Interventions Other Jurisdictions Are Trying
Governments with substantial condominium markets have begun intervening at the points where buildings and owners are under the greatest pressure. None has repaired its entire condo market, and several programs remain narrow, underfunded or unfinished. But they recognize that repairs, assessments, insurance and carrying costs can become housing-policy problems.
| Jurisdiction | Intervention | What it is intended to address |
|---|---|---|
| Miami-Dade County | Zero-interest loans of up to $50,000 for eligible owners facing special assessments for required repairs | Helps owners pay assessments so associations can complete necessary work |
| Chicago | Preservation financing, governance training and technical assistance for condo and co-op associations | Gives resident associations access to capital and help managing building repairs |
| Hawaii | A $20 million association loan program and a reopened hurricane-insurance option for qualifying properties | Connects repair financing with the insurance problems that can obstruct unit financing |
| New York City | Property-tax abatements for eligible resident owners and rehabilitation incentives for qualifying buildings | Reduces some owner carrying costs and offsets some building-renovation expenses |
| California | Expanded FAIR Plan access and disaster-area nonrenewal protections for qualifying condominium associations | Provides a limited insurance backstop where private coverage is difficult to obtain |
| Connecticut | Common Interest Community Common Element Repair Loan Program: association loans for significant common-element capital repairs when comparable commercial financing is unavailable; associations generally contribute at least 20% of the project cost | Helps qualifying associations finance major repairs to roofs, roadways, central heating plants and other common elements |
| Montgomery County, Maryland | Common Area Assistance Loan Fund: zero-interest loans of up to $500,000 directly to qualifying condominium and homeowner associations | Helps associations complete urgent common-area health and safety repairs involving elevators, fire-suppression systems, water lines, façades, balconies, drainage systems and parking structures |
The results are uneven. Miami-Dade’s loans have income and funding limits. Hawaii’s association loan program is new, so its reach and results have not yet been established. Chicago’s documented assistance remains targeted rather than citywide. New York City’s newest rehabilitation expansion still requires final approval.
Those limitations do not make the interventions meaningless. They show how difficult the problem is and why a program must be funded, accessible and operating before a financing crisis reaches the closing table.
In addition to having no legislative requirements governing reserve studies and funding, the District of Columbia has no operating condo-specific repair initiative or other functioning program designed to assist associations in financial distress. An old Common Interest Community Repairs provision remains in the DC Code, but it has no publicly available application, dedicated current funding or demonstrated record of delivering assistance. A program that exists only on paper cannot help the DC buildings now confronting higher insurance costs, depleted reserves, major capital projects and more demanding lender reviews.
DC Is Moving in the Other Direction
Oddly, The DC Council is considering measures that could actually place additional pressure on the condominium market.
One is the idea of a pied-à-terre tax on high-value non-primary residences. No bill, rate, threshold or definition has been proposed, but the concept is scheduled for discussion as part of the Council’s October 16 search for additional revenue. Pied-à-terres are disproportionately condominiums in my experience because they offer security, building services and lock-and-leave convenience. A tax aimed at that ownership pattern could discourage a buyer segment particularly well suited to DC condos at the moment the market needs more buyers, not fewer. Before advancing any pied-à-terre tax, the Council should estimate how many affected properties are condominiums, where they are concentrated and whether the tax could reduce demand in already weak segments of the condo market.
The Council also has before it Bill 26-0495, the Condominium Insurance Amendment Act. The bill would raise the maximum master-policy deductible that an association can pass through to the owner of the unit where a loss originates from $5,000 to $25,000. It would require expanded owner insurance and mandate waivers of subrogation in unit-owner policies, restricting an insurer’s ability to recover money from a responsible third party after paying a claim.
Associations face real insurance problems, including larger deductibles and rising master-policy premiums. Shifting more of that exposure to individual owners does not eliminate the cost. It relocates it. An owner could face a deductible charge of as much as $25,000, higher HO-6 coverage requirements and fewer avenues for an insurer to recover a loss caused by a negligent neighbor or an association-level failure.
That financial exposure follows the unit into the sales process. Buyers and their lenders examine association deductibles, insurance requirements and potential assessments because each one affects the buyer’s future housing cost. A Council bill designed to relieve pressure on associations can simultaneously make ownership more expensive and less predictable for the people purchasing and selling the units.
The Intervention DC Has Not Designed
The D.C. Council doesn’t control mortgage rates, national insurance pricing or the project standards used by Fannie Mae and Freddie Mac. It is too late to properly assess the magnitude of the problem and build a meaningful repair-loan or assessment-assistance program in advance of the January 4th deadline.
But the Council can, and should, begin convening lenders, association managers, attorneys and reserve specialists, publishing a plain-language explanation of the new standards, surveying associations about reserve allocations and reserve studies, directing associations to existing qualified providers and industry guidance, requesting aggregate project-review data from lenders and the GSEs and reviewing pending tax and insurance measures for near-term effects on condo affordability and liquidity.
It can, once studies are complete, implement a phased intervention by amending the D.C. Condominium Act to require periodic reserve studies and appropriate funding plans, using incremental implementation to avoid imposing an immediate, uniform burden on associations. This would better align all associations with GSE underwriting guidelines, and with the standards of surrounding states like Maryland and Virginia.
Sources
Condominium Market Data
National Association of Realtors: Existing-Home Sales
National Association of Realtors: Existing Condo and Co-op Sales and Prices
SmartCharts: DC Condo Months of Supply
SmartCharts: DC Condo Absorption Rate
Condominium Financing Standards
Fannie Mae: Project Standards Requirements FAQs
Freddie Mac Guide Bulletin 2026-C
CNBC: Condominium Financing Changes and the Former Limited-Review Market
Association Reserves: National Reserve-Funding Data
Reserve-Study and Funding Requirements
District of Columbia Condominium Act
Maryland Condominium Act § 11-109.4: Reserve Studies
Maryland House Bill 292: Reserve-Account Funding and Funding Plans
Virginia Condominium Act § 55.1-1965: Annual Budget and Reserve Study
Virginia Resale Disclosure Act
Programs and Interventions in Other Jurisdictions
Miami-Dade County: Condominium Special Assessment Loan Program
Chicago: South Shore Condo/Co-op Preservation Fund
Hawaiʻi Green Infrastructure Authority: Condominium Association Loan Program
Hawaiʻi Hurricane Relief Fund: Condominium and Apartment Association Coverage
New York City: Cooperative and Condominium Property-Tax Abatement
New York City: J-51 Reform Rehabilitation Tax Incentive
California Department of Insurance: FAIR Plan Expansion
California Department of Insurance: Mandatory Nonrenewal Moratoriums
Connecticut Housing Finance Authority: Common Interest Community Common Element Repair Loan Program
Montgomery County, Maryland: Common Area Assistance Loan Fund
Maryland SB 446: Local Condominium and HOA Repair and Rehabilitation Funds
DC Laws, Programs and Proposals
D.C. Code § 42-2072: Common Interest Community Repairs Program
D.C. Code § 42-2073: Common Interest Community Repairs Program Eligibility
D.C. Code § 42-2857.01: Department of Housing and Community Development Unified Fund
DC Council: Condominium Insurance Amendment Act of 2025, Bill 26-0495
DC Council Hearings and Public Meetings
DHCD Residential and Community Services Programs
Disclaimer: The information provided on this site is for general informational and educational purposes only and does not constitute professional real estate, legal, or financial advice. While we strive to keep information accurate and up-to-date, topic details, property details, market conditions, prices, and availability are deemed reliable but not guaranteed. Readers should conduct their own independent due diligence and consult with a licensed real estate broker, attorney, CPA, financial advisor or appropriate District of Columbia government agency to verify information and policy. Content subject to change without notice. realestateinthedistrict.com and dcrealestate.channel, their owners, operators and writers disclaim any liability for any loss or damage-arising directly or indirectly from the use of or reliance on any information provided on this blog. This blog and its affiliated social media channels are the sole property and responsibility of their owner, and are not affiliated with Compass International Holdings (CIH).