The Freshest Washington DC Data.
The DC real estate market is constantly evolving. Stay ahead of trends and shifts with weekly and monthly data and summaries.
Comprehensive. Detailed. Understandable.
District of Columbia Weekly Market Data
DC City Weekly Data
| BRIGHT MLS DATASET | WEEK ENDING OCT. 4 | PRIOR YEAR | PRIOR WEEK |
|---|---|---|---|
| WEEKLY SHOWINGS | 2,141 | 2,377 | 1,964 |
| NEW SALES CONTRACTS | 118 | 135 | 147 |
| MEDIAN DAYS TO CONTRACT | 50 days | 43 days | 35 days |
| NEW LISTINGS | 251 | 274 | 289 |
| MEDIAN LIST PRICE | $735,000 | 698,750 | 649,000 |
| ACTIVE LISTINGS | 2,920 | 2,927 | 2,953 |
| % ACTIVE WITH PRICE DROP | 8.1% | 7.3% | 7.1% |
| CANCELED LISTINGS | 40 | 45 | 38 |
Anemic market activity once again resulted in an increase in median price in Washington D.C. last week.
Showing activity in DC increased from the prior week but remained below last year. New sales contracts fell both week over week and year over year, while median days on market rose sharply to 50 days, up from 35 days the prior week and 43 days a year ago. New listings also declined, while active inventory was little changed from either comparison period.
The share of active listings with a price reduction increased to 8.1%, from 7.1% the prior week and 7.3% a year ago. Canceled listings rose from 38 to 40 week over week but remained below last year’s 45. The median list price climbed to $735,000.
Washington DC Metro Area Weekly Data
The DC Metro Area market consists of District of Columbia, Arlington Va, Alexandria Va, Alexandria City Va, Fairfax County, Fairfax City, Falls Church, Montgomery County Md, Loudoun County Md, and Frederick County Md.
| BRIGHT MLS DATASET | WEEK ENDING OCT. 4 | PRIOR YEAR | PRIOR WEEK |
|---|---|---|---|
| WEEKLY SHOWINGS | 14,794 | -14.2% | +2.1% |
| NEW SALES CONTRACTS | 893 | -19.5% | -5.7% |
| MEDIAN DAYS TO CONTRACT | 36 days | +6 days | +2 days |
| NEW LISTINGS | 1,412 | -1.3% | -1.5% |
| MEDIAN LIST PRICE | $625,000 | +2.5% | +1.6% |
| ACTIVE LISTINGS | 12,525 | +19.6% | -0.1% |
| % ACTIVE WITH PRICE DROP | 10.4% | +0.2 pp | +0.2 pp |
| CANCELLED LISTINGS | 199 | +48.5% | +15.0% |
Buyer activity across the DC Metro remained weak during the week ending October 4th. New contracts fell 5.7% from the previous week and were 19.5% below the same week last year. Showings improved 2.1% week over week, but remained 14.2% below last year’s level. Homes also stayed on market longer, with the median time from listing to contract pushing up to 36 days, six days longer than a year ago.
Inventory remains substantially higher than last year. Active listings totaled 12,525, nearly unchanged from the prior week but 19.6% above 2025. New listings were down slightly both year over year and week over week, suggesting that the elevated inventory is being sustained less by a surge of new sellers than by homes already on the market taking longer to sell.
Seller withdrawals are also becoming more noticeable. Canceled listings rose 15.0% in a single week and were 48.5% higher than a year ago. With contracts down sharply from last year while inventory remains elevated, some sellers appear to be choosing to leave the market rather than continue waiting for a buyer.
DC (City) Monthly Data
AUG 2026
Sept. 2026 data will be released Oct. 11, 2026
| METRIC | AUG 2026 | YOY | MOM |
|---|---|---|---|
| TOTAL SOLD DOLLAR VOL | $464,963,547 | -2.4% | -19.1% |
| AVG SOLD PRICE | $1,050,690 | +22.9% | +12.7% |
| MEDIAN SOLD PRICE | $681,500 | +1.7% | +1.3% |
| UNITS SOLD | 438 | -19.5% | -28.0% |
| AVG DAYS ON MARKET | 51 | +15.9% | +13.3% |
| AVG SP TO OLP | 95.7% | +0.5 pp | -0.2 pp |
| ACTIVE LISTINGS | 2,514 | -4.3% | -4.4% |
| NEW LISTINGS | 571 | -15.9% | -21.9% |
| NEW PENDINGS | 373 | -14.6% | -28.1% |
| ALL PENDINGS | 557 | -7.3% | -16.2% |
Source: SmartCharts Pro
Summary
August 2026 DC (City) Summary
Washington’s housing market slowed considerably in August, as is seasonally expected. Closed sales fell to 438, down 19.5% from August 2025 and 28% from July. New pending sales also weakened, falling 14.6% year over year to 373, while new listings declined 15.9%. With both buyers and sellers pulling back, active inventory actually finished the month 4.3% below its year-ago level.
Prices held up considerably better than transaction activity. The median sold price rose 1.7% from a year ago to $681,500, while the average sold price jumped 22.9% to more than $1.05 million. That unusually large increase in the average was heavily influenced by the mix of properties sold: detached homes averaged $2.27 million, up 49.4% from August 2025, despite only 72 detached sales.
The August numbers point to a market with fewer participants on both sides rather than a broad decline in prices. Homes that sold took longer, averaging 51 days on market compared with 44 last August, but sellers still received an average 95.7% of their original asking price.
DC Metro Area Monthly Data
AUG 2026
Sept. 2026 data will be released Oct. 12, 2026
| METRIC | AUG 2026 | YOY | MOM |
|---|---|---|---|
| TOTAL SOLD DOLLAR VOL | $3,975,361,184 | -4.5% | -15.8% |
| AVG SOLD PRICE | $731,298 | +2.3% | -1.4% |
| MEDIAN SOLD PRICE | $597,500 | +1.7% | -0.4% |
| UNITS SOLD | 5,404 | -6.5% | -14.9% |
| AVG DAYS ON MARKET | 31 | +6.9% | +10.7% |
| AVG SP TO OLP | 98.2% | +0.2 pp | -0.3 pp |
| ACTIVE LISTINGS | 15,366 | +12.9% | -1.0% |
| NEW LISTINGS | 5,978 | -3.8% | -15.9% |
| NEW PENDINGS | 5,207 | -10.4% | -10.6% |
| ALL PENDINGS | 6,565 | -5.4% | -9.1% |
Sources: Smart Charts Pro
Summary
August 2026 DC Metro Summary
The Greater DC housing market also slowed in August, although the decline was considerably less pronounced than in the District. Closed sales fell 6.5% from August 2025 to 5,404, while new pending sales declined 10.4%. New listings were down a more modest 3.8% year over year.
Prices remained relatively stable. The median sold price rose 1.7% from a year earlier to $597,500, while the average sold price increased 2.3% to $731,298. Homes took somewhat longer to sell, averaging 31 days on market compared with 29 days last August, while sellers received an average 98.2% of their original asking price.
Unlike DC City, however, the broader region continues to carry substantially more inventory than it did a year ago. Active listings totaled 15,366, 12.9% above August 2025, even after slipping 1% from July. That combination of higher inventory and a 10.4% year-over-year decline in new pending sales suggests buyers across the region had more choices while demand softened heading toward the fall market.
The Condominium Market: Washington DC’s Weakest Link
One of the biggest stories of the past two years has been the steady deterioration of the District’s condominium market. While other property types have held up better, condominiums and co-ops remain the weakest segment of Washington’s housing market and account for a disproportionate share of the city’s available inventory.
The distress of the market hasn’t always been visible in reported data, though. That’s because prices were holding up remarkably well in the face of significant inventory increases, slowing sales pace and other market indicators that get overshadowed by pricing data.
Here’s the market in three charts. First, the pricing data for sold units that makes the market appear healthy. But beneath it, the chart showing available inventory. It’s at a ten year high. In green (the little bars at the bottom of the blue inventory markers), the absorption rate for that inventory. It’s at a 10 year low.
And finally, Days On Market. The ten year high was reached in February. The spring market shaved it somewhat, but by the end of July it was rising again, ending August at 58 days.
That is the true picture of DC’s condo market. Pricing for units sold looks healthy. But few units are selling relative to supply, so that picture is deceiving.
Through August, 1,812 condos and co-ops had sold in 2026, down 10.9% from 2,034 during the same period last year. New pending contracts were down a similar 10.2%. Yet the median sold price for the first eight months of the year was unchanged at $490,000.
The slowdown is more visible in the measures of market liquidity. August ended with 1,469 active condo and co-op listings. Homes that sold had spent an average of 67 days on the market, compared with 48 days in August 2025 and a five-year August average of 47 days. The contract ratio fell to 0.13 pending contracts per active listing, down from 0.18 a year earlier and roughly half the five-year August average of 0.25.
August itself was particularly weak for transactions: 187 condos and co-ops closed, 29.2% fewer than a year earlier, while new pending contracts fell 31.2% to 137. One month shouldn’t be treated as a trend by itself, but those readings are consistent with the longer January-through-August decline in sales and contract activity. The result is not a broad decline in the prices recorded by successful sales. It is a condo market completing fewer transactions, taking longer to produce those transactions, and carrying more available inventory relative to current contract activity.
Condos are highly reactive to market and economic conditions and often show changes in buyer demand earlier than other housing types. The District’s condominium market was beginning to recover from the severe demand disruption of the pandemic when DC’s economic trajectory changed again in early 2025. Federal employment and spending uncertainty added another challenge to a market already contending with high mortgage rates and rising ownership costs. Since then, tighter condominium financing and insurance requirements have added further pressure to the buyer pipeline.
At the close of September 2026, the 30-year mortgage interest rate had risen to 7.58% [MND]. Key drivers are spiking 10-year Treasury yields (near 10 year highs), global bond market sell-offs, persistent inflation (at 3.4% for the 12 months ending in August 2026), increased federal government deficits, the Iran war, and the expectation of at least one more 25-basis-point rate hike by the Fed before the end of 2026.
Declining Values
So why haven’t condo prices fallen further? Part of the answer is in the math. Many condo sellers simply don’t have as much room to cut their prices. Condominiums tend to have thinner equity margins than more expensive property types, particularly when the owners purchased recently or financed with relatively small down payments.
Unlike detached homeowners who often:
- Bought years ago
- Accumulated significant appreciation
- Paid down principal
- Have flexibility to negotiate;
many condo owners:
- Purchased more recently
- Put 3–10% down
- Paid peak-pandemic prices (this is the part where you care more about what you paid for your condo than what you pay per month)
- Financed mortgage insurance
- Paid premiums on new construction
- Experienced little or no appreciation and in many cases loss
- Continue paying rising HOA dues, insurance and utility costs.
Their margins are erased, or even negative.
When prices soften, it doesn’t matter a great deal to those with 40% equity, but it is a sale-killer for others. And as inventory levels continue to rise, prices continue to lower, widening the gap between what’s owed and current market value. Even modest price declines can make it difficult to sell without bringing cash to closing, leaving some owners effectively trapped in their homes.
Washington’s condominium market has historically depended on two primary buyer groups:
The first is first-time homebuyers. Condominiums have long served as the entry point into homeownership for young professionals beginning careers in government, law, consulting, lobbying, nonprofits, healthcare, and related industries. These buyers traditionally purchase a condominium as their first home before moving up to a rowhouse or detached property;
The second is part-time or pied-à-terre buyers. Members of Congress, federal executives, diplomats, attorneys, corporate executives and other professionals have historically purchased condominiums because they wanted a low-maintenance residence close to Capitol Hill, downtown, or federal agencies. They weren’t necessarily looking for the least expensive housing, they were buying convenience, security and a lock-and-leave lifestyle.
Both groups have backed off.
Certainly the first-time buyer pool shrank because affordability deteriorated, mortgage interest rates rose, and cratering federal employment caused many younger households to search elsewhere. But also, the city’s overall desirability has suffered over the past two years. According to the D.C. Policy Center, domestic out-migration increased to 6.0 per 1,000 residents (up from 0.6) and international migration declined to 5.7 per 1,000 residents (down from 9.2). Overall grew slightly by 0.3% entirely by natural increase (births minus deaths), not migration.
That’s a real problem for condominiums.
Condominiums are not just another housing type in Washington. They are the foundation of the District’s homeownership ladder. When fewer buyers enter through that first rung, fewer owners move up to larger homes, reducing liquidity throughout the entire housing market.
Unfortunately, the challenges facing condominium owners are poised to become even greater.
Beginning this summer, Fannie Mae and Freddie Mac are implementing sweeping underwriting changes that will make financing more difficult for many condominium and cooperative buildings. Higher reserve funding requirements, stricter reserve study standards, lower deductible thresholds, and the elimination of limited reviews for most projects will leave many underfunded or poorly managed associations unable to meet agency standards. Buyers may not discover that a building is non-warrantable until late in the financing process, causing transactions to fail just before closing.
At the same time, the DC Council is considering the Condominium Insurance Amendment Act of 2025 (B26-0495), legislation that would substantially increase the financial exposure of condominium owners by raising deductible pass-through limits, expanding insurance requirements, and requiring broad waivers of subrogation. Although presented as consumer protection, the proposal could shift significantly more financial risk from condominium associations onto individual owners, particularly in situations where the origin of property damage is disputed, a common occurrence in multifamily buildings.
The Council is also considering a pied-à-terre tax similar to the program now under fire in NYC. This would disproportionally affect condominiums.
Taken together, these trends suggest the District’s condominium market is no longer facing a temporary cyclical slowdown, it’s undergoing a structural shift. A smaller pipeline of first-time and part-time buyers, rising ownership costs, tighter financing standards and additional legislative uncertainty are all reducing the buyer pool. Until that buyer pipeline begins to expand again, condominiums are likely to remain the weakest segment of Washington’s housing market, and the first place where broader economic changes become visible.
Mortgage Rates And Impact
Septamber 2026
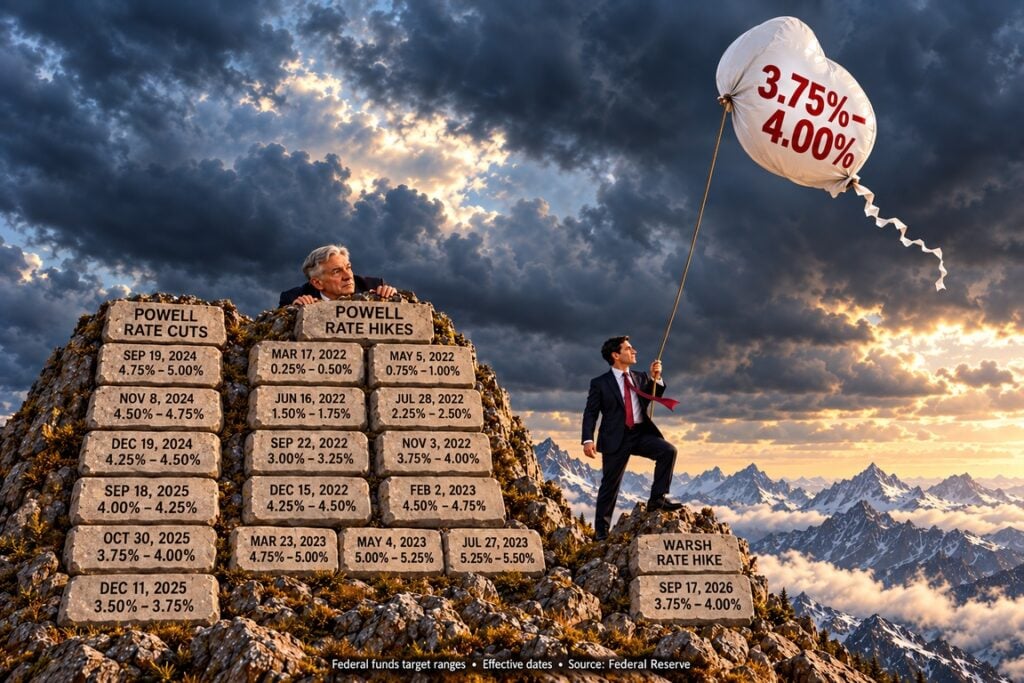
The Federal Reserve raised its benchmark interest rate by 25 basis points to a range of 3.75%–4.00% following the FOMC meeting in September, indirectly pushing average 30-year fixed mortgage rates to around 6.76%, though most mortgage lenders had already priced in the move.
Then rates continued to rise. By the end of September, the 30 year mortgage rate had passed 7.5%.
How the Fed Rate Affects Housing
Fixed mortgages track long-term bond yields such as the 10-year Treasury note. When the benchmark rate rises signaling a tighter economy, bond yields and mortgage often rise in response.
Since higher interest rates raise monthly mortgage payments, many buyers take a step back from the market, impacting home sales volume.
Homeowners are also affected because borrowing costs increase overall. Home Equity Lines of Credit (HELOCs) have variable rates, as do other adjustable rate mortgages. A Fed rate hike has an immediate effect on those products.
The home building industry is also impacted. Smaller builders rely on short-term loans to build houses and higher rates means costs rise and the final project increases in price to homebuyers. An unfriendly lending environment can also deter builders altogether, slowing down the creation of new housing supply.
Don’t expect drastic price drops as a result of higher mortgage rates. The norm is for prices to flatten, or rise slowly. Sellers often choose to remain in their homes or become landlords until conditions improve.
The Fed signaled that there would be at least one more rate hike this year and nearly half the board sees at least 2 more hikes in this cycle.
About The Author | Susan Isaacs
Professionally, I look for logic + upside in every situation, to the extent that it benefits my clients. I focus on market conditions supported by data, which helps make me a pricing and negotiation expert. My years of experience in this market lends perspective. My research in area and national market conditions provides a basis for market trajectory, valuable in making buying and selling projections. Above all, I am an informative and straight-forward communicator.
I represent residential real estate buyers and sellers in Washington DC and northern Virginia.