VantageScore® Could Open The Door For More DC Home Buyers
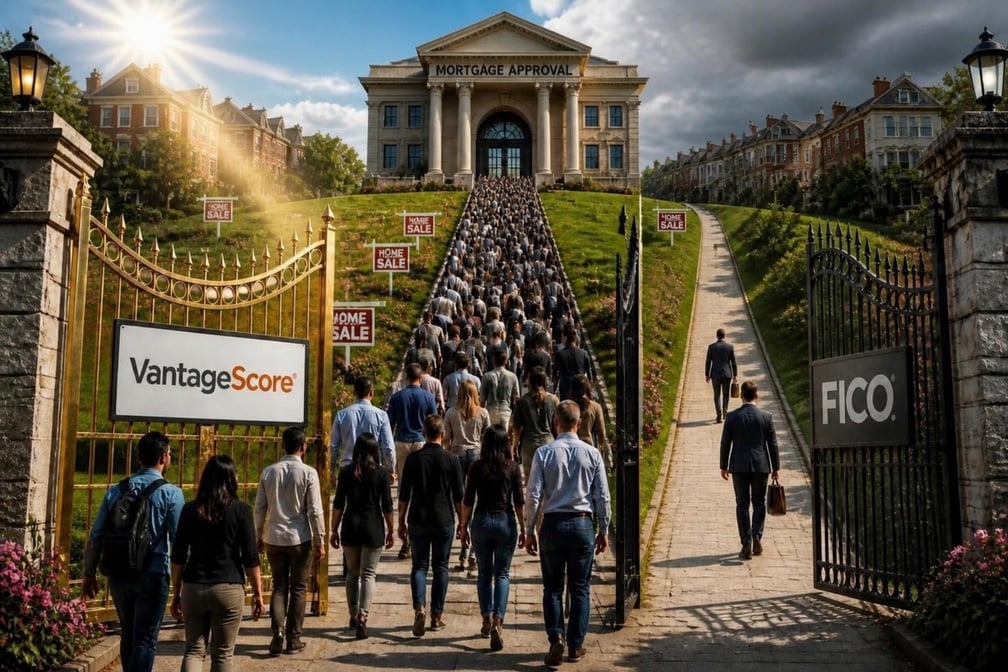
For decades, getting a conventional mortgage meant passing through the same gate: FICO. That rusty gate is still there, but now there’s a new one beside it. Mortgage shoppers compare interest rates, origination fees, closing costs, and loan terms. The next question for lenders may be: Which credit score do you use?
The Federal Housing Finance Agency just moved Fannie Mae and Freddie Mac to a single loan-pricing grid that puts VantageScore 4.0 alongside Classic FICO. “Loan-pricing grid” sounds like an obscure piece of mortgage machinery, but it simply means Fannie Mae and Freddie Mac charge lenders fees when they buy or guarantee certain mortgages. The lenders may pass those costs to borrowers through the interest rate, closing costs, or both. Loans evaluated with VantageScore and FICO were subject to different fee schedules, which complicated the choice between them. Putting both models on the same grid removes that variable, so the scoring model itself no longer determines which fee schedule applies. This makes it easier for lenders to choose an alternative to FICO.
FICO was highly profitable, and highly dominant. The new single loan-pricing grid creates badly-needed competition. Lenders will now be able to choose between two approved scoring models without one carrying a separate pricing framework. FICO retains its place in the mortgage system, at least for the time being, but lenders now have a viable path to shop for an alternative.
VantageScore® Is Inclusion-Coded
The fundamental divergence between VantageScore and FICO comes down to their philosophical design:
- VantageScore 4.0 is built for “Credit Inclusivity”: VantageScore actively tries to map out borrowers who have “thin files” or untraditional history. It can generate a credit score with a single account open 30 days. It also leans heavily on reported alternative data for buyers with “thin” credit files.
- FICO 10T is built for “Risk Precision”: FICO won’t even generate a score without a minimum six-month credit history. Instead of casting a wider net, it uses the 24-month trended data window to maximize predicting absolute default risk for traditional borrowers.
As VantageScore 4.0 is adopted by lenders, we’ll be able to judge its consumer benefits, which include financial inclusivity:
- Scoring roughly 33 million previously “credit invisible” consumers, expanding the pool of buyers who can qualify for a mortgage
- Establishing a valid credit score with only one month of history, compared to the six months traditionally required by FICO
- Incorporating rent, utility, and telecom payments when those payments are reported to the credit bureaus, allowing buyers to build credit through their everyday living expenses
- Accurately scoring millions of consumers with inactive credit histories who would otherwise be rejected by older systems
- Evaluating a broader range of financial behaviors, which helps thin-file buyers qualify for lower closing costs and better interest rates.
You can read more on the VantageScore website.
Following the announcement by FHFA, Rocket Mortgage, a unit of Rocket Companies (RKT), immediately announced it would “become the first mortgage lender to use VantageScore 4.0 as its preferred credit scoring model for all eligible loans.” It added that “after roughly four months of testing, the company found that VantageScore helped more clients qualify and move forward in the mortgage process, while also reducing credit scoring costs.”
FICO Hasn’t Been Winning Any Popularity Contests
Over the past two decades, FICO has made some truly punitive adjustments to its credit scoring models, targeting loopholes in credit-building, penalizing multi-month revolving debt behavior, and severely cracking down on sudden delinquencies.
Here are FICO’s Greatest Hits: The most damaging and unpopular policies FICO has unloaded on consumers over the last 20 years:
1. Penalizing consumers for having no reported revolving-card balances
FICO’s utilization logic can produce a lower score when every revolving account reports a zero balance. That creates the maddening impression that paying everything off, or not using credit at al, is somehow deficient. The model consequently deducts 10 to 25 points from credit scores. This pressures consumers to maintain expensive revolving debt they may not want or need just to keep their scores high.
2. Treating credit use as a requirement for proving responsibility
Young people just entering the workforce, people who avoid credit cards and rely on cash or Bitcoin, or those who simply have little borrowing history shouldn’t be treated like credit criminals. FICO (Classic) requires 6 months of history + activity. A thin file deems the consumer unscorable.
3. Leaving older FICO models hanging in the void
FICO keeps releasing new scoring models that promise to evaluate consumers more accurately. But instead of retiring outdated versions, it leaves them available for lenders to keep using. That distorts borrower risk profiles via outdated, non-preventative scoring math. A model that recognizes responsible debt consolidation, or evaluates payment behavior more fairly may exist, but consumers have no guarantee that a lender will use it. The older model remains available, familiar, and cheaper to maintain. FICO can then claim credit for improving its system while avoiding responsibility for the older versions still shaping major financial decisions. Consumers are left navigating a scoring system where the rules depend not only on their behavior, but also on which version a lender has chosen not to replace. This practice also leaves borrowers exposed to FICO 8’s older treatment of medical collections when reportable medical debt appears in the credit file.
4. The “Double-Debt” Personal Loan Trap
Debt consolidation is supposed to simplify a borrower’s finances: replace high-interest credit-card balances with one installment loan, then pay that loan down over time. But consumers who consolidate credit card debt using personal installment loans face compounded algorithmic penalties if their cash flow fluctuates. The model explicitly tracks credit card balances after debt consolidation loans and executes severe, rapid score drops for rising card balances. This creates a high-risk “double-debtor” penalty for recovering consumers;
5. Turning a temporary financial struggle into a long-term score problem
FICO 10T incorporates trended credit data, examining patterns in balances and payments over time rather than relying only on a single snapshot.That may help lenders predict risk. For consumers, it means a period of financial stress can remain visible long after their finances improve. Paying on time today may not erase the consequences of having carried high balances or made minimum payments months earlier. The model remembers the struggle even after the emergency has passed.
6. Making one late payment disproportionately damaging
A single late payment can cause a sharp score decline, especially for someone who previously had an excellent record. FICO’s modern models have systematically stripped away gradual recovery metrics, making single missteps increasingly devastating for prime borrowers. This policy amplifies the mathematical weight of fresh, isolated late payments and drops top-tier consumer scores significantly for one error. Years of responsible behavior can be erased because of an autopay failure, an address change, a disputed bill, or a short-term emergency. The model sees a serious delinquency. The consumer sees a temporary issue that has been turned into a long-term financial penalty.
7. Treating “credit invisible” consumers as risky
A thin credit file does not necessarily mean someone is irresponsible. The person may pay rent, use cash, avoid credit cards, or have recently entered the country. Yet lenders often have difficulty evaluating applicants without a conventional credit history. The absence of evidence becomes its own kind of evidence, and consumers can find themselves denied credit because they have not previously used enough credit to qualify. That makes the system particularly hostile to young adults, immigrants, low-income households, and anyone who has managed to live outside the standard borrowing system.
8. Making consumers navigate a maze of FICO scores
There is no single FICO score in practice. There are different model generations, bureau-specific versions, industry-specific versions, and lender-specific applications.The score a consumer sees through a credit-monitoring service may not be the score a mortgage lender, auto lender, or credit-card issuer uses. A borrower can watch one number rise and still receive a different evaluation when applying for credit. Consumers are asked to improve a score without being told which score will actually decide their fate.
9. Keeping the scoring process opaque while making it economically decisive
FICO provides broad explanations of the factors that influence scores: payment history, balances, credit history, new accounts, and types of credit. But consumers can’t inspect the formula or know precisely how a particular decision was produced. That would be irritating if the score were merely informational. It becomes punitive when the number affects access to a home, car, insurance policy, a loan or even a job; and when lenders may use different versions of it.
10. Trended Data and Persistent Utilization
FICO 10T and VantageScore both use Trended Data and Persistent Utilization. VantageScore was the first to roll it out. But the two are quite different when it comes to penalties. FICO 10T and VantageScore 4.0 handle the weight of your balances using fundamentally different core logic:
VantageScore 4.0
Under VantageScore 4.0’s official weighting, your score is driven heavily by two distinct categories:
- Payment History (41%): Making your minimum payments on time keeps this category positive and prevents a catastrophic default drop.
- Credit Utilization (20%): Carrying a persistent high balance means your utilization ratio remains dangerously high every single month.
Making on-time payments prevents your score from completely collapsing into the default zone. But, being classified as a steady “Revolver” with high utilization will severely anchor your score. For an excellent credit rating, you must transition from a Revolver to a Transactor by paying those balances down.
| Debt Trajectory | 20% Utilization Impact | Trended Data Assessment | Score Outcome |
|---|---|---|---|
| Paying in Full (Transactor) | Minimal to None (~0-10%) | Exceptionally low risk | Excellent Score |
| High & Spiking (Chorer) | Maximum Penalty | High risk of near-term default | Rapidly Collapsing Score |
| High & Flat (Stable Revolver) | Maximum Penalty | Predictable risk, but overextended | Chronically Low/Stagnant Score |
Versus:
FICO 10T
FICO doesn’t isolate trended balance data into a separately published scoring category. Amounts Owed, which includes revolving utilization, accounts for roughly 30% of the traditional FICO scoring framework. FICO 10T adds a 24-plus-month history of balances to that picture. Instead of seeing only the latest reported balance, as older models largely did, 10T can distinguish whether balances have been falling, remaining persistently high, or increasing over time.
That means a borrower who has carried high revolving balances for two years can still benefit from paying them down before applying for a mortgage, and a rapid rescore can quickly reflect the new lower balances. But under FICO 10T, the new balance doesn’t erase the preceding history. The current utilization may improve while 10T can still see the balance trajectory that Classic FICO couldn’t.
How FICO 10T Uses Balance Trajectory
| 24-Month Balance Trajectory | FICO 10T Can Distinguish | Potential Score Effect |
|---|---|---|
| Downward Trend (Transactor/Paying Down Debt) | Balances declining or being paid off rather than persisting | More favorable trajectory |
| Flat & High Trend (Steady Revolver) | High balances persisting month after month | Persistent revolving debt can work against the score |
| Upward Trend (Escalator) | Balances increasing over time | Higher-risk trajectory that can work against the score |
Another important distinction between the two models is transparency. VantageScore tells us considerably more about how trended behavior affects its scoring model. FICO confirms that trajectory affects 10T scoring, but keeps the magnitude proprietary.
11. Charging More
FICO is more expensive than VantageScore. Consumers don’t buy mortgage credit scores directly, lenders pay credit reporting agencies, but they pass these fees through to borrowers as part of the overall credit report or closing costs.
The cost varies depending on which wholesale model a lender chooses:
The Performance Model ($4.95 + Funded Fee): FICO offers a separate “performance” model where the upfront per-score royalty is reduced to $4.95 (which FICO markets as a 50% discount achieved by cutting out credit bureau markups). But this model carries a major catch: it tacks on a steep $33.00 closed loan fee per borrower per score once a mortgage actually funds.
The Traditional Per-Score Model ($10.00): If lenders choose to bypass FICO’s direct program and buy scores the traditional way through tri-merge reseller partners, FICO maintains a $10.00 per-score fee. This is the baseline “traditional benchmark” that Experian and TransUnion cite when pointing out that FICO doubled its traditional per-score pricing from $4.95 to $10.00.
VantageScore is priced significantly lower, with major bureaus offering rates around $0.99 to $4.50 through 2027/2028 to encourage market competition. Adoption of VantageScore 4.0 by Fannie Mae and Freddie Mac reduces overall industry costs, saves individual borrowers upwards of $100 per completed mortgage loan, per Equifax and VantageScore.
Comparing VantageScore Models
If you’re comparing the two models, and you should, be sure you’re looking at the newest version of VantageScore (4.0). VantageScore 3.0 is still widely shown on free consumer apps (like Credit Karma, WalletHub and even the recently updated and fact-checked Nerd Wallet), while 4.0 is the model used for advanced lending decisions and approved by Fannie Mae and Freddie Mac for mortgages.
VantageScore 4.0 uses machine learning and trended data to track credit behavior over time, whereas VantageScore 3.0 looks at a single snapshot of data. Both models share a 300 to 850 score range, but they differ significantly in data usage and factor weighting.
Model Comparison
| Feature | VantageScore 3.0 | VantageScore 4.0 |
|---|---|---|
| Data Type | Static snapshot | Trended (over time) |
| Technology | Traditional scoring | Machine learning |
| Payment History | 40% weight | 41% weight |
| Credit Utilization | Prior month only | Up to 24 months |
| Medical Collections | Included/Filtered differently | Excluded entirely |
| Alternative Data | Limited | Rent, utility, telecom |
Key Factor Weight Differences
Payment History: Weighted slightly higher in 4.0 (41%) compared to 3.0 (40%)
Recent Credit / Inquiries: Receives higher emphasis in 4.0 (11%) than in 3.0 (5%)
Total Balances: Decreases in emphasis from 3.0 (11%) down to 4.0 (6%)
Depth of Credit: Slips slightly from 3.0 (21%) to 4.0 (20%)
Available Credit: Drops from 3.0 (3%) to 4.0 (2%)
Inclusion: Version 4.0 can score over 33 million people with thin credit files by using alternative data like rent and utility payments
Utilization Tracking: Version 4.0 analyzes if your balances are trending up or down over a two-year period rather than just checking last month’s statement.
How FICO Controlled The U.S. Credit Market For 35 Years
Equifax, Experian, and TransUnion controlled the underlying credit files of American consumers, but had no scoring model. FICO controlled the part lenders cared most about: the standardized numerical score used to translate those files into lending decisions.
FICO introduced its general-purpose credit score in 1989 and established a powerful distribution arrangement.
Each bureau supplied the consumer’s credit data and FICO’s bureau-specific model converted that data into a score. The bureau delivered the report and score to the lender. FICO collected licensing or royalty revenue through its contractual agreement with that bureau. That arrangement produced a two-sided dependency.
Once lenders had built underwriting rules, pricing tables, regulatory processes, investor disclosures, and historical performance databases around FICO, replacing it became expensive and risky. Now it was a three-sided dependency. A competing score wasn’t useful just because it predicted defaults well; lenders also needed years of validation, internal approval, compatible systems, and acceptance by mortgage-market institutions and investors. An FTC (Federal Trade Commission) conference transcript described FICO scores as those “most widely used by creditors.” The mortgage market strengthened the FICO lock-in. FICO’s de facto dominance was described as a “virtual monopoly” in credit scoring by the Yale School of Management.
Even after regulators approved VantageScore 4.0 in 2022, implementation remained a major industry roadblock rather than a simple software replacement. For roughly three and a half decades FICO remained deeply embedded in the market. FICO controlled the market by becoming its common language, like “Google.” The bureaus possessed the raw information, but FICO supplied the algorithms that produced scores the lenders, mortgage institutions, and investors had standardized around. Once that standard was embedded in contracts, software, underwriting policies, and decades of loan-performance data, the bureaus couldn’t realistically withhold FICO without making their own products less useful.
Until…
The GSEs stepped in. Fannie Mae and Freddie Mac are the gatekeepers for a huge portion of the U.S. mortgage system. If they accept a scoring model, lenders can use that model on mortgages intended for sale to the government-sponsored enterprises. That gives the model scale, legitimacy, and a route into mortgage-backed securities.
On July 8, 2025, FHFA announced that lenders would be able to use VantageScore 4.0 or Classic FICO for mortgages sold to Fannie and Freddie (Freddie Mac). That was a major structural change, though rollout was phased rather than instantaneous: Freddie Mac reported beginning a limited rollout with approved sellers in April 2026, and Fannie Mae initially made VantageScore available through a limited group of approved lenders (Fannie Mae).
This gives VantageScore real market share, not just theoretical approval. The change breaks FICO’s mortgage-market exclusivity. Lenders selling conventional mortgages to Fannie and Freddie can break out of the FICO-centered system. In the past, a lender might have liked another score, but that didn’t matter much if the resulting mortgage couldn’t move smoothly through the dominant secondary-market channels. FHFA acceptance of VantageScore changes that. FICO is no longer the only commercially viable score for this part of the mortgage market. It has to compete for lender adoption rather than being the required standard.
FICO now has to defend its price and performance against an approved alternative.
When Is This Thing Happening?
The pricing framework itself is effectively live now, but broad lender adoption will probably take 6 to 18 months. A near-complete industry transition could take two to three years, assuming Fannie and Freddie keep supporting both VantageScore 4.0 and Classic FICO.
The key distinction is between GSE implementation and market adoption. Fannie Mae broadened VantageScore 4.0 availability on September 9, 2026. It updated its loan-level price-adjustment matrix to explain how loans submitted with VantageScore will be priced (in a Fannie Mae lender letter). Its implementation materials say lenders may now originate and sell eligible loans using VantageScore 4.0. That pricing grid was the missing commercial piece and now it’s in place. Lenders needed to know which score would determine the applicable LLPA and how VantageScore-scored loans would be treated economically. Fannie has now supplied those rules. So, technically, this is no longer a multiyear implementation proposal. Lenders can begin using the model right now.
Large lenders will need to update their loan-origination systems, pricing engines, credit-report interfaces, disclosures, quality-control rules, and fair-lending monitoring, so that’s going to take some time. They’ll also need to validate how VantageScore affects approval rates and pricing across their customer base. Mortgage companies rarely move every channel at once. A lender might first use VantageScore in its retail channel, with selected borrower groups, or when it produces a score where Classic FICO doesn’t. Wholesale and correspondent channels may follow later because they involve more outside parties and contractual changes. Investors and secondary-market desks also need experience with these loans.
But the exciting news is that early VantageScore loans are already appearing in GSE pools. The market has little model-specific prepayment or performance history, but Fannie and Freddie published additional historical VantageScore 4.0 data in July 2026 to help market participants analyze the model’s performance. That data should help investors compare pools. Still, building confidence takes time.
Here’s a guesstimated timeline:
- Now through early 2027: Early adopters and technologically prepared lenders begin using VantageScore on eligible loans. Some will use it selectively rather than replacing FICO across the board;
- During 2027: Adoption should broaden as credit-report vendors, mortgage software providers, aggregators, and correspondent investors complete integrations. This is when the pricing-grid decision is likely to become visible in ordinary mortgage operations;
- By late 2027 or 2028: VantageScore could become a normal second option across much of conventional lending, provided the GSE rules remain stable and loan performance doesn’t produce unexpected concerns;
- Beyond 2028: A true marketwide rebalancing between FICO and VantageScore will depend on lender economics, investor acceptance, model performance, and whether the GSEs continue permitting a choice or eventually standardize around a newer model.
Have a preference? Tell your lender.
What This Means in the DC Housing Market
Washington DC has a stubborn affordability problem. Many households have stable employment and solid incomes, yet high home prices, hefty closing costs, rising monthly utility and insurance fees, and home type-related costs such as condo dues and up-front capital contributions, can make qualification difficult.
What may seem like a relatively small difference in how a credit file is evaluated may matter. A stronger score could affect whether an applicant clears a lender’s threshold or how a loan is priced within the applicable grid. But buyers shouldn’t assume VantageScore 4.0 will always produce the higher number. The models weigh credit behavior differently, so one borrower may score better under VantageScore while another may fare better under FICO. At least now there’s a choice.
The change may be especially relevant to first-time buyers who have stable careers and manageable debt but shorter credit histories. It could also help buyers whose responsible financial habits are not fully reflected by a traditional scoring model.
There is an equity dimension, too. Consumers with thin files aren’t necessarily irresponsible borrowers; many simply use fewer traditional credit products. One could call that very responsible. A model capable of scoring more of those consumers could broaden the pool of people who receive meaningful mortgage consideration.
“Broader access” doesn’t mean weaker underwriting. Lenders will still verify employment, income, assets, debts, down-payment funds, property value, and numerous other details. The purpose of an additional scoring model is not to approve applicants who cannot afford a home. It is to reduce the chance that an otherwise credible buyer is excluded because one model cannot adequately interpret the available data.
Three Questions Buyers Should Ask Their Lender
DC home buyers shouldn’t wait until underwriting to learn how their lender handles credit scoring. Before applying for a mortgage loan, or even authorizing multiple credit pulls for a pre-approval, ask three direct questions:
- Do you currently offer loans evaluated with VantageScore 4.0?
- Can you evaluate my file under both approved models?
- Would a different scoring model change my eligibility, interest rate, or upfront fees?
Borrowers should get answers in writing when possible. “We accept VantageScore” is not quite the same as “we can use VantageScore for your credit pull today.”
Sources
- Fannie Mae 2025 Form 10-K
- Federal Housing Finance Agency, Credit Scores. FHFA credit-score policy, approval history, lender choice between VantageScore 4.0 and Classic FICO, and implementation
- Fannie Mae, Lender Letter LL-2026-06: VantageScore 4.0 Broad Lender Availability. Broad VantageScore 4.0 availability and aligned loan-level pricing for Classic FICO and VantageScore 4.0
- Fannie Mae, Credit Score Models and Reports Initiative. Fannie Mae implementation requirements and credit-score model transition
- Freddie Mac, Credit Score Models and Reports Initiative. Freddie Mac implementation chronology, VantageScore 4.0 availability, and historical credit-score data
- VantageScore 4.0 User Guide. Technical documentation for VantageScore 4.0, including model design, trended credit data, and scoreability
- VantageScore 4.0 Model Attributes. VantageScore’s description of its use of trended credit data and expanded scoreable population
- FICO, FICO Score 10 Suite. FICO’s introduction of FICO 10 and FICO 10T and the use of trended credit-bureau data
- myFICO, FICO Score Versions. FICO 10T and the use of trended balances and credit-limit information
- myFICO, What’s in Your FICO Scores?. FICO’s traditional scoring-factor framework and relative importance of payment history, amounts owed, credit-history length, new credit, and credit mix
- myFICO, Amounts Owed. FICO’s explanation of amounts owed, revolving utilization, and the relationship between debt and scoring
- FICO, Mortgage Direct License Program. FICO’s mortgage-score licensing and pricing structure
- Fair Isaac Corporation, Fiscal 2020 Form 10-K. FICO’s historical credit-bureau distribution relationships, licensing arrangements, and revenue concentration
- Fair Isaac Corporation, Fiscal 2023 Form 10-K. FICO business and competitive-risk disclosures, including risks associated with changes in GSE use of FICO scores
- Rocket Companies, September 28, 2026 VantageScore Announcement. Rocket Mortgage’s adoption of VantageScore 4.0 as its preferred scoring model for eligible loans following approximately four months of testing
- Experian, VantageScore 4.0 Mortgage Pricing. Experian’s $0.99 standalone mortgage-origination pricing for VantageScore 4.0
- TransUnion, VantageScore 4.0 Mortgage Pricing. TransUnion’s $0.99 standalone mortgage-origination pricing through the end of 2028
- Equifax, VantageScore 4.0 Mortgage Pricing. Equifax’s VantageScore 4.0 mortgage-score pricing and discussion of increased competition in mortgage credit scoring
- CreditRise, Mortgage Credit Score Rules 2026: What FICO 10T and VantageScore 4.0 Mean for Your Home Loan. Consumer-credit analysis of trended data and the transactor, steady-revolver, and escalator balance patterns
- Federal Trade Commission, Fourth Annual Microeconomics Conference Transcript, 2011. FTC discussion of FICO scores as the credit scores most widely used by creditors
- “The”Virtual monopoly” statement originates from research published by the Thurman Arnold Project at Yale University, an antitrust and competition policy initiative based at the Yale School of Management.