What stands out
- Buyer demand is still soft in the District120 new contracts in the subject week (ending Oct 11), down 13.7% from a year ago and about level with the 118 the week before that. Median days to contract held at 50, up from 41 a year ago.
- List prices pulled back as showings laggedThe median list price of $615,000 is 1.4% below last year and well under the previous week’s $735,000, a swing weekly medians can show when the mix of new listings changes. Showings ran 8.0% below last year.
- September closings slipped, prices mostly held398 DC sales closed in September, down 6.8% from a year ago. The median sold price was $660,000, down 2.9%.
- Inventory differs between city and regionDC had 3,041 active listings at the end of September, 1.1% above last year. The metro area had 17,704, up 21.4%.
- Detached sales rose while condo sales fellDetached closings were up 46.6% from a year ago (85 against 58). Condo and co-op closings were down 16.3% to 154.
- Condos are the weak segment0.12 pending contracts per active condo listing in September, against a five-year September average of 0.23.
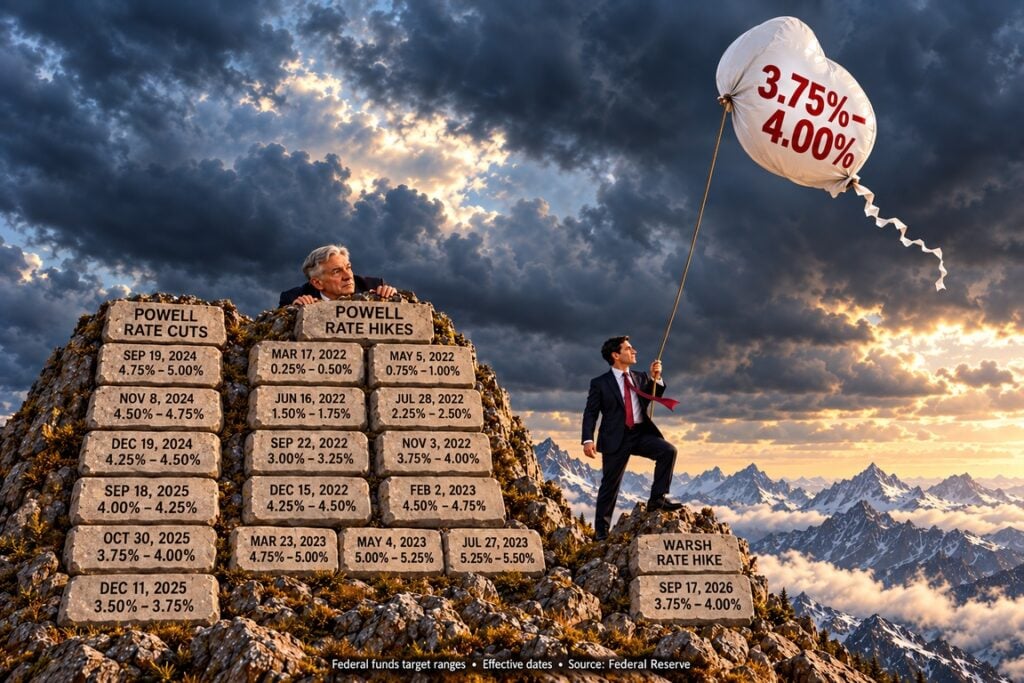
- Mortgage rates rose through SeptemberThe 30-year rate hit 7.58% on Sep 29, after the Fed raised its range by 25 basis points to 3.75%–4.00%.
Washington DC Week Ending Oct 11
Week ending Oct 11 · vs. Prior year and Previous weekWeekly activity, three periods
District of Columbia · Bright MLSComparisons: Year over Year, Previous week and Subject week. Bars start at zero.
DC vs DC Metro Area | Year over Year
Week ending Oct 11DC changes are calculated from the weekly figures on the source page (subject week against the same week a year ago). Metro changes are as published. The metro area covers DC, Arlington, Alexandria, Fairfax County and City, Falls Church, Montgomery, Loudoun and Frederick.
View weekly data as tables
District of Columbia
| Metric | Subject wk | Yr ago | Prev wk |
|---|---|---|---|
| Showings | 1,912 | 2,079 | 2,140 |
| New sales contracts | 120 | 139 | 118 |
| Median days to contract | 50 days | 41 days | 50 days |
| New listings | 241 | 247 | 251 |
| Median list price | $615,000 | $624,000 | $735,000 |
| Active listings | 2,986 | 2,955 | 2,920 |
| Active with price drop | 8.2% | 7.1% | 8.1% |
| Canceled listings | 39 | 29 | 40 |
DC Metro Area (changes as published)
| Metric | Subject wk | vs. yr | vs. wk |
|---|---|---|---|
| Weekly showings | 13,636 | ▼−15.7% | ▼−7.8% |
| New sales contracts | 912 | ▼−15.5% | ▲+2.1% |
| Median days to contract | 40 days | ▲+7 days | ▲+4 days |
| New listings | 1,326 | ▼−0.5% | ▼−6.1% |
| Median list price | $590,000 | ▼−0.8% | ▼−5.6% |
| Active listings | 12,720 | ▲+20.6% | ▲+1.6% |
| Active with price drop | 9.8% | ▲+0.4 pp | ▼−0.6 pp |
| Canceled listings | 154 | ▲+11.6% | ▼−22.6% |
September 2026 sales
Monthly data · SmartCharts Pro| Metric | Sep 2026 | YoY | MoM |
|---|---|---|---|
| Total sold dollar volume | $351,984,861 | ▼−3.0% | ▼−24.3% |
| Average sold price | $870,012 | ▲+3.6% | ▼−17.2% |
| Median sold price | $660,000 | ▼−2.9% | ▼−3.2% |
| Units sold | 398 | ▼−6.8% | ▼−9.1% |
| Average days on market | 46 | ▼−2.1% | ▼−9.8% |
| Average sold-to-original-list price | 95.7% | ▲+0.3 pp | –0.0 pp |
| Active listings | 3,041 | ▲+1.1% | ▲+21.0% |
| New listings | 1,067 | ▼−6.9% | ▲+86.9% |
| New pendings | 499 | ▼−9.3% | ▲+33.8% |
| All pendings | 603 | ▼−9.5% | ▲+8.3% |
Closed sales fell 9.1% from August and 6.8% from September 2025. Active listings rose 21.0% from August, and new listings nearly doubled (+86.9%) as the market came back from its August low. Homes that sold averaged 46 days on market, against 51 in August and 47 a year ago.
| Metric | Sep 2026 | YoY | MoM |
|---|---|---|---|
| Total sold dollar volume | $3,448,655,200 | ▼−7.3% | ▼−13.2% |
| Average sold price | $698,622 | ▲+0.2% | ▼−4.5% |
| Median sold price | $569,000 | ▼−0.2% | ▼−4.8% |
| Units sold | 4,903 | ▼−7.4% | ▼−9.3% |
| Average days on market | 33 | ▲+3.1% | ▲+6.5% |
| Average sold-to-original-list price | 97.6% | ▼−0.2 pp | ▼−0.6 pp |
| Active listings | 17,704 | ▲+21.4% | ▲+15.2% |
| New listings | 7,412 | ▲+1.2% | ▲+24.0% |
| New pendings | 4,886 | ▼−16.7% | ▼−6.2% |
| All pendings | 6,099 | ▼−14.0% | ▼−7.1% |
The metro area carries far more inventory than a year ago: active listings are 21.4% above September 2025 and 15.2% above August. New listings rose 1.2% from a year ago while new pendings fell 16.7%, and homes averaged 33 days on market, against 32 last September.
DC by property type
September 2026 · year-over-year| Type | Closed | YoY | Median | YoY | Avg DOM | Active | Contract ratio |
|---|---|---|---|---|---|---|---|
| Detached | 85 | ▲+46.6% | $1,064,500 | ▼−16.5% | 47 | 383 | 0.31 |
| Townhouse (attached) | 159 | ▼−13.6% | $795,000 | ▼−5.4% | 39 | 921 | 0.30 |
| Condo and co-op | 154 | ▼−16.3% | $499,950 | ▲+2.1% | 51 | 1,737 | 0.12 |
Detached homes made up 85 of 398 closings (21%), against 58 of 427 (14%) a year ago. That mix shift lifts the citywide average sold price even as the median fell. The contract ratio is pending contracts per active listing.
Condos and co-ops in DC
Through September 2026The median sold price for January through September is $490,000, against $489,000 a year ago. Fewer units are selling relative to the supply on the market.