A cooler inflation report and weak September jobs report have deflated expectations for a rate increase by the Federal Reserve later this month.
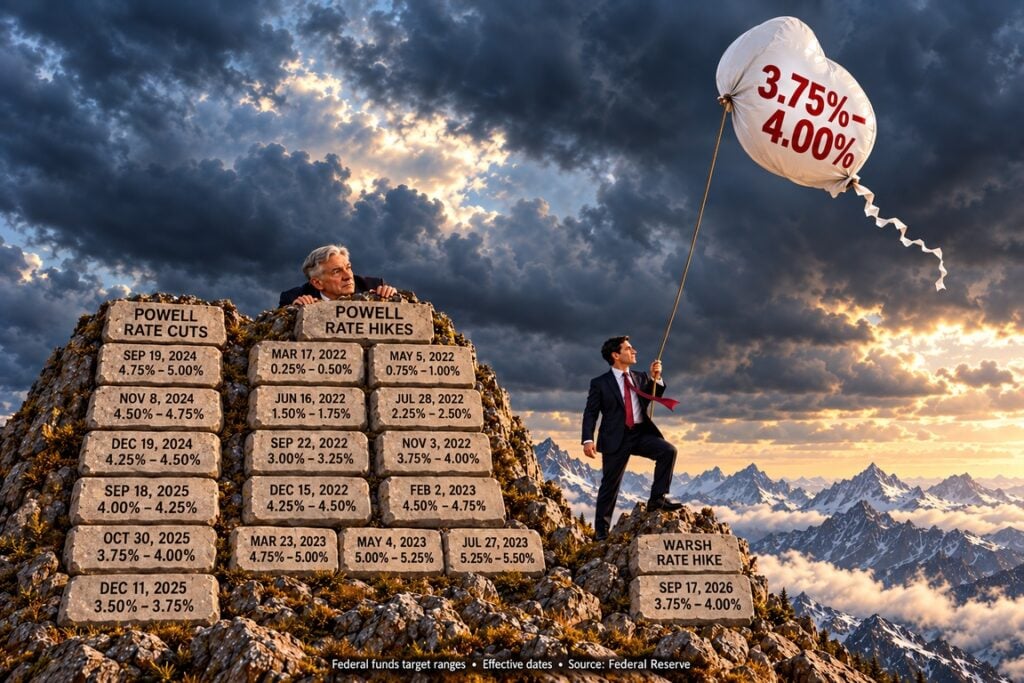
A week can make quite a difference. Last Friday, futures markets were pricing in a 64.2% probability that the Federal Reserve would raise its target rate another quarter point at its October 27-28 meeting. By 9:00:56 a.m. Eastern Friday, that probability had fallen to just 17.2%, according to the CME FedWatch snapshot shown below. The probability that the Fed leaves its target range unchanged at 3.75% to 4.00% moved the other way, from 35.8% a week ago to 82.8% Friday morning. That’s a fairly dramatic repricing of what the market thinks the Fed will do next.
First inflation, then jobs
Two economic reports helped produce it. The first arrived Wednesday, when the Bureau of Economic Analysis released its August Personal Consumption Expenditures data. The headline PCE price index rose 0.3% for the month and 3.4% from a year earlier. Core PCE, which excludes food and energy, increased 0.2% for the month and 3.0% over the year.
Inflation certainly hasn’t disappeared. The Fed’s target is still 2%, and Fed Vice Chair Philip Jefferson noted Thursday that inflation has remained above that target for more than five years. But the August PCE reading came in below expectations. Reuters reported that economists had expected a 3.7% annual increase, and the softer result quickly reduced expectations for another increase in October.
Then came Friday morning’s employment report. The Bureau of Labor Statistics reported at 8:30 a.m. Eastern that the U.S. economy added only 29,000 jobs in September, while the unemployment rate edged up from 4.1% to 4.2%. Average hourly earnings increased just 0.1% for the month and 3.0% from a year earlier.
The revisions were ugly, too. July’s initially reported gain of 21,000 jobs was revised down to a loss of 10,000, while August was revised from 162,000 to 133,000. Together, the two revisions erased 60,000 previously reported jobs.
The September report doesn’t describe an economy falling off a cliff. BLS itself said both payroll employment and unemployment “changed little,” and Reuters noted that there has been no broad increase in layoffs. But the report does describe a labor market with considerably less momentum than the August number had suggested. Payroll growth averaged only 45,000 a month over the preceding 12 months, according to BLS.
Markets reacted immediately. Treasury yields fell after the report, with the two-year Treasury yield, particularly sensitive to expectations for Fed policy, initially falling as much as eight basis points. Reuters reported that the market-implied probability of an October hike fell as low as 12% before moving back toward 21% as trading continued.
The Financial Times framed the jobs report as another significant blow to the case for an October increase. Thomas Simons, chief U.S. economist at Jefferies, was considerably less delicate, calling the September employment number “the nail in the coffin for an October hike.” My snapshot of CME data, taken at 9:00:56 a.m. Eastern, captured the same rapid repricing: FedWatch put the probability of no change at 82.8% and the probability of a quarter-point increase at 17.2%. The market had already been moving away from an October hike after the inflation report and comments from Fed officials. The jobs report pushed it further.
The Fed was already signaling patience
New York Fed President John Williams had already pushed back against the idea that the Fed needed to move quickly. Speaking Tuesday at the University at Buffalo, Williams said that after September’s rate increase there was “no need for urgency.” He said another upward adjustment might be appropriate late this year if the economy evolved as he expected, while emphasizing that incoming data would determine the timing, according to Reuters.
Fed Vice Chair Philip Jefferson reinforced that message Thursday, though he didn’t say the same thing as Williams. In a speech at the University of Virginia’s Darden School of Business, Jefferson said future policy adjustments should be determined by “carefully examining trends in the data, the evolving outlook, and the balance of risks.” Reaching the Fed’s judgment, he said, “may take more time.” Friday’s employment report gave policymakers another reason to take it. [Federal Reserve]
That doesn’t mean another rate increase isn’t forthcoming. Reuters reported Thursday that Goldman Sachs had moved its forecast for the next 25-basis-point increase from October to December after the softer PCE report. Following Friday’s employment report, Lindsay Rosner, head of multi-sector fixed-income investing at Goldman Sachs Asset Management, told Reuters that “October seems unlikely” and that one follow-up increase in December remained the firm’s base case. She also cautioned that market pressures and higher energy prices could still force the Fed’s hand sooner.
Minneapolis Fed President Neel Kashkari has also left the door open. He told Reuters Thursday that he expects additional rate increases will be needed, but said he was open-minded about the timing and didn’t have a strong view about whether the next one should come at the October meeting.
What this could mean for mortgage rates
For homebuyers and sellers, the immediate question isn’t simply what the Fed does with the federal funds rate. Mortgage rates aren’t set by the Fed. They’re influenced by the broader bond market and expectations about inflation, economic growth and future monetary policy.
Friday’s jobs report relieved some of the pressure there. Treasury yields fell after the release as investors reduced expectations for near-term Fed tightening. The 10-year Treasury yield fell three basis points in Reuters’ post-release market snapshot after moving lower earlier in the session. That doesn’t guarantee an equivalent decline in mortgage rates, and one weak employment report doesn’t establish a new rate trend. Inflation is still running above the Fed’s target, energy prices remain a risk, and Fed officials continue to contemplate additional tightening.
NAR Chief Economist Lawrence Yun described Friday’s jobs report as an economy that is neither approaching recession nor overheating and said mortgage rates could see some relief after their sharp rise over the past month. His explanation was that the softer labor market should exert less upward inflation pressure, while oil prices had also retreated.
But the Fed doesn’t have to start cutting rates for mortgage conditions to improve. If inflation and employment data are soft enough to keep another immediate rate increase on the sidelines, bond markets can begin doing some of the work first. For now, that’s the story in the FedWatch chart: the market hasn’t decided that higher rates are over. It has decided that October looks a lot less likely than it did a week ago.
Sources
- Bureau of Labor Statistics: September 2026 Employment Situation | Origin source. September payroll employment (+29,000), unemployment (4.2%), average hourly earnings (+0.1% monthly, +3.0% annual), and the July and August revisions totaling 60,000 fewer jobs. BLS also establishes the report’s 8:30 a.m. Eastern release time. Bureau of Labor Statistics
- Bureau of Economic Analysis: August 2026 Personal Income and Outlays | August 2026 Personal Income and Outlays: August PCE data
- CME FedWatch Tool : CME states that FedWatch probabilities are derived from 30-Day Fed Funds futures. Rate probabilities attributable to “CME FedWatch.” The post chart is taken from the October 2 CME snapshot captured for this article. CME Group
- Federal Reserve: Vice Chair Philip Jefferson, “The U.S. Economy and Monetary Policy,” October 1, 2026: Origin source. Jefferson’s speech at the University of Virginia’s Darden School of Business. Direct source for his statement that future policy adjustments should be determined by “carefully examining trends in the data, the evolving outlook, and the balance of risks,” and that reaching policymakers’ judgment “may take more time.”
- Financial Times: September jobs report and Fed reaction
- Reuters: John Williams sees no urgency for next Fed hike
- Reuters: Goldman Sachs pushes Fed hike forecast to December
- Reuters: Market reaction to September jobs report
- Reuters: Kashkari on further rate increases
- Reuters: “Fed’s Williams sees no urgency for next rate hike,” September 29, 2026: Contemporaneous reporting of Williams’s remarks. Source for New York Fed President John Williams’s statement in Buffalo that there was “no need for urgency” following September’s rate increase, and for his comments about the possibility and timing of another increase. This is Reuters reporting rather than a Federal Reserve transcript. Reuters
- Reuters: “Fed policymakers lean against October rate hike,” October 1, 2026: Contemporaneous reporting and context. Reports the developing case among Fed policymakers for waiting before another increase and provides contemporary market context for the Williams and Jefferson remarks. Jefferson’s quotations in the post are nevertheless sourced to his Federal Reserve transcript. Reuters
- Reuters: Goldman Sachs moves its next Fed hike forecast from October to December: Reporting of proprietary Goldman Sachs analysis. Source for Goldman’s decision, following the PCE report, to move its forecast for the next 25-basis-point increase from October to December. This is not a Goldman Sachs origin document.
- Reuters: Market reaction to the September jobs report, October 2, 2026: Contemporaneous reporting and proprietary analyst commentary. Source for the immediate Treasury-market reaction and for Goldman Sachs Asset Management’s Lindsay Rosner saying “October seems unlikely” and describing a December increase as the firm’s base case. Rosner’s comments were provided to Reuters, so Reuters is the appropriate attribution in the prose. Reuters
- Financial Times: “US economy adds just 29,000 jobs in September as hiring slows sharply,” October 2, 2026: Contemporaneous reporting and analyst reaction. Source for the FT’s analysis of the employment report and its effect on expectations for additional Fed tightening, including Thomas Simons of Jefferies describing the report as “the nail in the coffin for an October hike.” Financial Times
- Reuters: “Fed’s Kashkari expects more rate hikes, unsure on need to act this month,” October 1, 2026: Contemporaneous reporting of Kashkari’s remarks. Source for Minneapolis Fed President Neel Kashkari’s expectation that further increases may be needed and his uncertainty about whether the Fed needs to act in October. Reuters
- Reuters: “US inflation rises below expectations in August, gives the Fed breathing space,” September 30, 2026: Contemporaneous reporting and expectations context. Used for the market/economist interpretation of the PCE release, including that inflation came in below expectations. The actual PCE figures in the article come from BEA, not Reuters. Reuters
Disclaimer
The information provided on this site is for general informational and educational purposes only and does not constitute professional real estate, legal, or financial advice. While we strive to keep information accurate and up-to-date, topic details, property details, market conditions, prices, and availability are deemed reliable but not guaranteed. Readers should conduct their own independent due diligence and consult with a licensed real estate broker, attorney, CPA, financial advisor or appropriate District of Columbia government agency to verify information and policy. Content subject to change without notice. realestateinthedistrict.com and dcrealestate.channel, their owners, operators and writers disclaim any liability for any loss or damage-arising directly or indirectly from the use of or reliance on any information provided on this blog. This blog and its affiliated social media channels are the sole property and responsibility of their owner, and are not affiliated with Compass International Holdings (CIH).