by Susan Isaacs | Mar 25, 2026 | Blog, 2025 Blog
A Condo Lending Reset Is Coming
It’s not every day that the rules of condo lending are fundamentally rewritten. But that’s exactly what’s happening right now; at a time when DC condo sales have slumped to a ten-year low.
Mid-March 2026, government-sponsored enterprises (GSEs) Fannie Mae and Freddie Mac announced a sweeping overhaul of their evaluation requirements for condominium mortgage financing.
Framed as ‘simplifications’, the new rules represent a major structural reset; one that will reshape how condo transactions are approved, delayed, and denied.
Phase I
First, The “Positives”
Fannie Mae and Freddie Mac’s new 2026/27 condo guidelines target lower insurance costs and easing of financing for certain smaller or investor-heavy projects.
Key Provisions
- Reduced Insurance Costs: By moving from strict Replacement Cost Value (RCV) to Actual Cash Value (ACV) for roofs, and establishing a $50,000 cap on per-unit deductibles (but it’s unlikely this will result in homeowners seeing lower insurance premiums since insurance rates are dramatically rising and the DC Council has chosen this time to push a bill increasing the deductible pass-through cap from $5,000 to $25,000, requiring owners to carry expanded insurance coverage, and mandating a waiver of subrogation across all policies);
- Increased Financing Eligibility For Certain Projects: Some relaxed rules, including removing the 50% investor concentration limit for established projects and expanding waivers for projects with up to 10 units, are aimed at making it easier to secure financing–only if other provisions of the new requirements (such as elevated reserves requirements) are met;
- Improved Market Access: By relaxing strict, “overly rigid” requirements for insurance, more condos in areas with high insurance rates or a heavy concentration of investors will be eligible for loans–but again, only if they meet other requirements.
- Streamlined Insurance Documentation: Lenders can now use insurer statements or appraisals to confirm coverage sufficiency, rather than needing to meet the stricter documentation requirements currently in place.
The Much Less Positive
The GSE Blacklist
Fannie Mae and Freddie Mac keep a Condo Project Advisor (blacklist) of buildings they deem ineligible for financing (nonwarrantable) due to safety issues, high deferred maintenance, insufficient reserves, active or pending significant litigation, hotel or resort-like characteristics with transient occupancy (short term rentals), high percentage of commercial space, and/or inadequate insurance coverage. A spot on the list renders condominium projects ineligible for conventional loans, leaving potential buyers with few options (high-interest specialty loans or cash sales). Think your building won’t make the list? Check the criteria:
How a Condo Makes The GSE Blacklist
Condos are listed if they fail to meet safety, structural, or financial requirements:
- Deferred Maintenance: Unaddressed “critical repairs” involving structural integrity, water intrusion, or safety systems
- Insufficient Reserves: HOA reserves are too low to fund needed repairs (minimum reserve funding increases from 10% to 15%)
- Special Assessments: Large, ongoing, or pending special assessments suggest financial instability
- Inadequate Insurance: Failure to meet Fannie/Freddie’s high insurance standards, such as lacking adequate flood or wind insurance
- Delinquent HOA Fees: High percentage of owners (15%+) behind on dues
- Investor Concentration: Too many units owned by investors rather than residents.
With new GSE guidelines issued this March, that list is about to expand considerably. Here’s why:
The End of the Fast Track
For years, condo lending relied on a two-track system:
- Limited Review: A streamlined, faster approval process
- Full Review: A slower, comprehensive and document-heavy approval process
That system is ending.
Effective August 3, 2026, Limited Review will be all but eliminated and Full Review becomes the default.
A narrow waiver applies only in limited cases.
For the tens of millions of Americans who rely on condominiums as an entry point to homeownership, which totals some 10-12% of all housing stock, and count on proceeds from the sale of those condominiums for their next step up the property ladder, the changes could mean an enormous loss in equity and a pronounced downturn in the already beleaguered condo market.
The “Limited Review” process has been the norm for condo financing for many years. Roughly 40% of all condo transactions have relied on this streamlined approval route, which allowed buyers and lenders to sidestep some of the most burdensome documentation requirements. If a condo project met certain basic criteria, it could be approved for conventional loans without exposing the lender or borrower to the full weight of bureaucracy.
That was then. Full Review is now. And the change will be seismic.
What Does It Mean For Mortgage Loan Underwriting?
- More documentation
- More scrutiny
- More time
- Higher costs for buyers and less profit for sellers
Under Full Review, lenders must evaluate:
- HOA financials and budgets
- Reserve funding
- Insurance coverage
- Structural and maintenance conditions
Many projects will:
- Face delays
- Require additional documentation
- Fail eligibility altogether
The Narrow Exception: Waiver of Project Review
A limited waiver exists for:
- Projects with 2–10 units, but those with 5–10 units cannot be part of a master association
Challenging because many urban developments operate within layered governance structures.
What About New Construction?
New construction projects must allocate at least 15% of annual budgeted assessments into replacement reserves starting January 4, 2027.
If a project uses a reserve study, it must adopt the highest recommended funding level instead of a baseline method.
If you’re buying now, make sure these provisions are already stated in the condo documents.
The Phase II Condo Crusher
Reserves Requirements Increase
After 2026 changes the process, 2027 changes the math as minimum reserve funding increases from 10% to 15%.
For many associations, this is not a minor adjustment, but a fundamental shift in financial expectations. And a good number will fall short.
Most condo associations don’t even meet the current 10% threshold.
While some experts say healthy associations should allocate 20% to 40% towards reserves, the industry norm is far lower. Many associations set aside far less, sometimes walking the thin line between scraping by and insolvency to keep monthly dues low. As a result, when the 15% rule takes effect, a significant portion of condos that are currently considered “warrantable” (meaning they qualify for conventional financing) will suddenly become “non-warrantable.”
Buyers won’t be able to get standard loans for these properties.
The consequences are profound. When a condo becomes non-warrantable, the pool of potential buyers shrinks dramatically because without conventional financing, the only remaining option is specialty loans with higher interest rates and down payment requirements. As demand drops, so do home values. Owners who bought at the peak could find themselves underwater, unable to refinance or sell without taking a significant loss, through no fault of their own.
For DC condo owners whose property values have already fallen steeply due to the pandemic, elevated mortgage interest rates, federal job losses and–in some neighborhoods–crime, options are few. While owners of single family homes can become ‘unintentional landlords’ in similar circumstances, condo owners find themselves hamstrung by condo rental restrictions and long waiting lists.
The timing for Fannie and Freddie’s rule changes couldn’t have been worse. Most associations approve their budgets months in advance of each new calendar year. Their budgets for 2026 and first quarter 2027 are already locked in, with no room to adjust reserve allocations before the new requirements hit. Local lenders estimate that up to 30% to 40% of older or smaller DC condos will become non-warrantable by January 2027. And the window for compliance is narrowing by the day.
“Most DC condo buyers pay cash anyway,” I was told by a board member of one at-risk association. He said it flippantly, shrugging off the new requirements. Such an attitude is not only ill-informed and elitist, but a dereliction of fiduciary duty.
While it’s often true that cash buyers are the norm for ultra-luxury buildings, the vast majority of DC condos in low to moderate price ranges (up to $1M) are financed. In two high-end neighborhoods where cash is routinely king, West End and Georgetown, the percentage of cash sales was particularly high in 2025. In West End, a whopping 59% of condo sales were all-cash transactions, as opposed to 41% financed. And in neighboring Georgetown, 54% cash. But the majority of cash sales were in ultra-luxury and investor-heavy buildings. In the $200k–$700k range, DC condo sales are between 70% and 80% financed. For financed owners in all buildings, warrantability is most definitely an issue.
“Condos occupy a structurally important position on the housing affordability ladder, as they are often the most affordable ownership option in high-density, high-cost urban environments. They are frequently the only form of ownership available at prices moderate-income and first-time buyers can afford, particularly in markets where land costs have significantly narrowed the range of ownership options.”
—The Urban Institute, June 2026 Research Report On Condominiums
Board members owe a fiduciary duty to all owners, not only the wealthy and investors. They should consider that if 41% of owners in the ‘entry-level’ price point see their values drop into the negative range, being unable to sell to financed buyers will further restrict their buyer pool and put downward pressure on already sinking values. If owners who must sell and are restricted from renting can’t absorb significant losses, short sale and foreclosure rates will rise, lowering values even more, harming every owner in those buildings.
How to Calculate The 15%
The association’s annual replacement-reserve allocation must equal at least 15% of its annual budgeted assessment income, calculated under Fannie Mae’s rules. The Selling Guide divides the reserve line by budgeted assessment income, and four categories come out of the bottom of that fraction first: incidental income, owner-type utilities like bulk cable, income allocated to reserves, and special assessments.That isn’t necessarily 15% of the association’s total revenue. This is not a change, the requirement was always calculated in this manner. The exclusions are permitted, not automatic. The lender applies them to the association’s actual budget. So owners should provide the budget along with seller disclosures, and buyers can ask their loan officer which income lines they excluded and what denominator they landed on when making the calculation.
Is This Really Happening?
Mortgage and real estate ndustry professionals raised the alarm, but the GSEs didn’t backtrack. Their stated reasoning is reportedly based on the need to protect consumers against the kind of systemic risk that led to the 2008 financial crisis. With loosening of mortgage guidelines by senior leadership in the current White House administration, the risk is genuine. Yet this ‘solution’ could have just as catastrophic effect on the condo market as the market crash of ’08. It feels similar to the knee-jerk action of the Fed drastically hiking interest rates repeatedly in 2022 to cool the economy: employing a sledgehammer response after taking too little incremental action for far too long.
Individual buyers, sellers and condo buildings won’t be the the only ones affected. If enough condos become non-warrantable, entire neighborhoods could see home values plummet. Cities like the District of Columbia that rely on condos to house a significant share of their population could face a cascading series of financial shocks, as property taxes fall and local economies suffer. It’s already happening in the District due to federal job losses and government actions. Added stress to a key component of the DC housing market could have serious and long-lasting consequences.
The transition is being handled with little transparency and even less coordination. Lenders, real estate agents and condo associations are calling for a delay or phased implementation of the reserve requirement, to give associations time to catch up. Others are pushing for more targeted waivers or alternative financing options. For now, August 3rd and January 2027 will mark a dramatic turning point in American housing; a point at which the promise of condo ownership, the foundation of the housing ladder for many, dismantles.
What To Do Now
Condo Buyers
- Confirm financing eligibility before making an offer
- Make offers contingent upon financing and the condominium meeting GSE underwriting guidelines
- Expect longer timelines
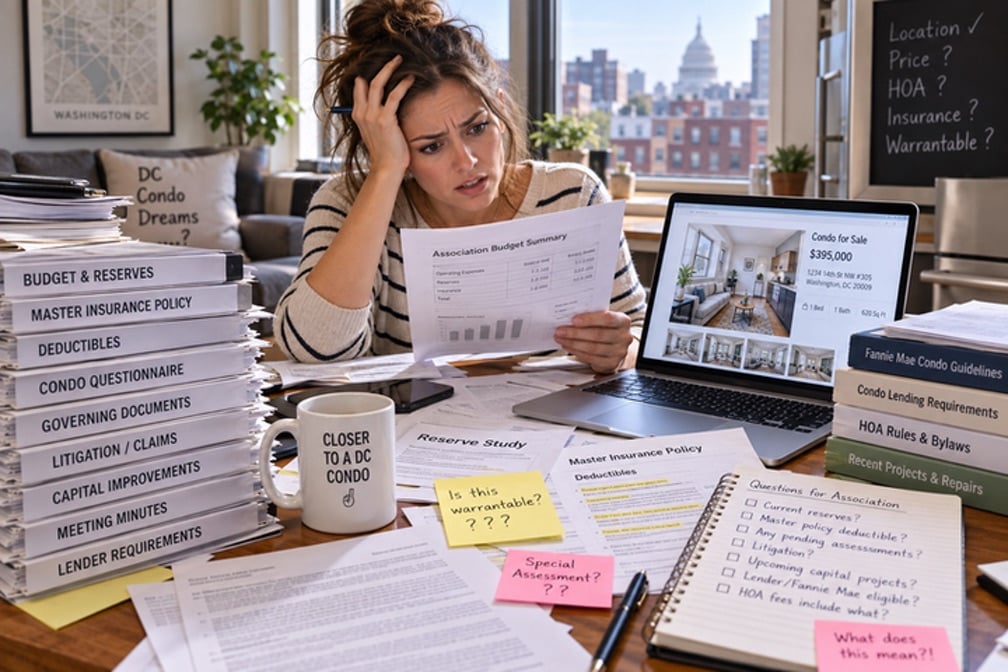
- Review HOA financials carefully. If possible, hire a CPA for help
- Be prepared for limited loan options in some buildings
- Consider the potential consequences of purchasing a condominium unit in an association that failed to meet GSE standards
In short, don’t just ask; “Do I qualify?” Ask; “Does the building qualify?”
Condo Owners
- Share this information
- Research your building’s current financials and condition. Ask whether your building would pass Full Review today
- Request plans from your board for needed changes
- Monitor reserve funding and upcoming budget changes
- Become active in your association, attend meetings, vote
- Prepare for increased buyer scrutiny
- Recognize that timing may impact marketability
- Price for project conditions, not just unit conditions
The financial health of a condo building is no longer a background detail.
It is becoming a primary driver of value, liquidity, and market access.
And as these rules take hold, the definition of a “financeable condo” will quietly, but meaningfully, change. Be prepared.