What UAD 3.6 Could Mean for Homebuyers
Homebuyers may soon pay hundreds more for an appraisal, but see no change in home valuation.
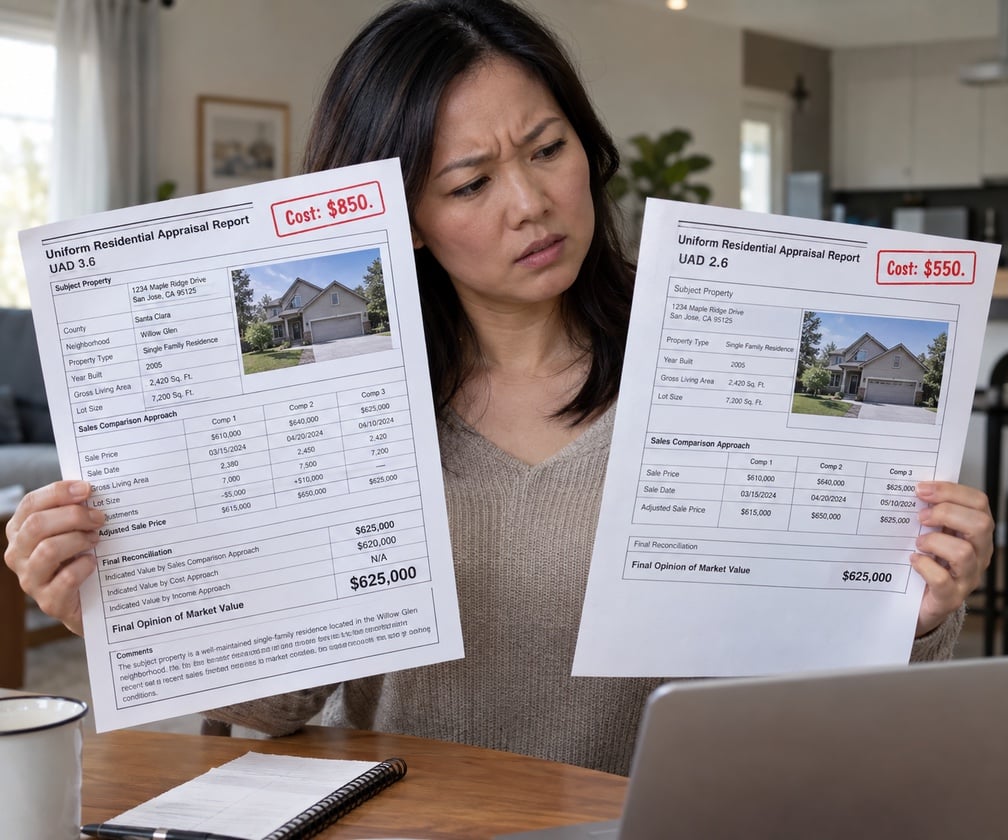
Home appraisals are moving from a decades-old system of fixed forms to a new data standard known as UAD 3.6. The transition is disrupting the mortgage industry and costs may land on consumers through higher appraisal fees and longer wait times. Michael Farrell, president of the National Association of Mortgage Brokers (NAMB), told Scotsman Guide that older-format appraisals are typically priced around $550, while reports completed under UAD 3.6 may cost closer to $850. because appraisers need updated software and training to complete UAD 3.6 reports. He also expects the new reports to take an additional three to five days to prepare since appraisers will need more time to gather information at the property and complete the redesigned reports.
Appraisal fees vary by location, property complexity, turnaround time and appraiser availability. Still, a possible $300 increase raises an obvious question: What does the borrower get for the hefty price increase?
Short answer: A more detailed, standardized appraisal report that takes longer to produce, not necessarily a more accurate valuation.
What is UAD 3.6?
UAD stands for Uniform Appraisal Dataset. It is the standard used to organize appraisal information submitted to Fannie Mae and Freddie Mac. UAD 3.6 is a major update to that standard. It introduces a redesigned Uniform Residential Appraisal Report, or URAR, that replaces several older forms with a single, flexible report for one to four-unit properties. The new report uses more standardized fields and adjusts based on the property and appraisal assignment. It’s submitted as a package containing structured data, a PDF report and related images.
UAD 3.6 doesn’t create a new way to calculate a home’s market value. Appraisers still use established valuation methods. The main change is how they collect, document and submit property information for the appraisal report.
When does the UAD 3.6 Requirement Kick In?
Key dates:
- November 2, 2026: UAD 3.6 becomes mandatory for new appraisal submissions. Approved exceptions allow continued use of UAD 2.6.
- March 1–May 19, 2027: Lenders with approved exceptions can still submit UAD 2.6 reports, but collateral-review functionality is reduced and certain appraisal-related lender protections no longer apply.
- May 20–June 27, 2027: All new submissions must use UAD 3.6. Previously submitted UAD 2.6 reports can still be resubmitted.
- June 28, 2027: UAD 2.6 submissions and resubmissions end completely.
These deadlines concern submissions to the Uniform Collateral Data Portal, not appraisal orders or closing dates.
For mortgages delivered to Fannie Mae or Freddie Mac, UAD 3.6 generally becomes mandatory for new appraisal submissions on Nov. 2, 2026. Some approved lenders have temporary exceptions that allow them to continue using UAD 2.6 through May 19, 2027.
These requirements concern appraisals submitted through the GSE system for loans involving Fannie Mae and Freddie Mac. Though the majority are, not every mortgage is delivered to the GSEs. FHA, VA, USDA, jumbo and portfolio loans can follow different appraisal rules.
Are homebuyers getting a better appraisal in exchange for a higher fee?
UAD 3.6 may produce a more detailed and standardized appraisal report, but that does not necessarily mean the homebuyer receives a more accurate valuation.
The new standard changes how appraisers collect, document and submit property information. It gives lenders, Fannie Mae and Freddie Mac more structured data for quality control and risk analysis. It replaces heavy narrative addendums with standardized, machine-readable data fields. UAD 3.6 requires more specific data points, including separate exterior and interior ratings, room-level detail for kitchens and bathrooms, structured HVAC and roof details, energy efficiency features, a change in area terms from “gross living area + basement” to “above-grade finished area and below-grade finished area,” and also requires detailed image packages.
But the basic methods used to estimate a home’s value remain largely the same, so the consumer benefit is not obvious. Borrowers seem to be paying more for a reporting system designed primarily to serve lenders and the government-sponsored enterprises.
Reported prices of $550 and $850 are not universal. Those figures come from one industry leader’s observations, not a nationwide study of appraisal fees.
Will UAD 3.6 make challenging an appraisal easier or harder?
The new standardized format and structured data replace subjective commentary that created “gray areas” open for interpretation. This could make it easier to pinpoint exact factual errors, such as incorrect square footage, missing property updates, or misstated condition ratings.
UAD 3.6 reports breaks down components like upgrades, systems, and finishes with greater granularity, so borrowers and agents can target an ROV with precise, documented proof. This includes things like permits, exact replacement dates, and contractor receipts.
But UAD 3.6 may also mean time delays in contesting appraisals. During early implementation, temporary delays, learning curves, and software transitions mean lenders and appraisers are still adjusting to new workflows. This could slow the process of handling disputes or revisions.
Will UAD 3.6 make it harder to get fair evaluations of unique, historic or unusual properties?
On the plus side, replacing the single broad quality rating with highly specific, room-by-room material and condition details can allow appraisers evaluating historic homes to isolate and explicitly detail period-accurate craftsmanship or specialized restorations rather than letting them get lost in a generic overview. And, to counteract the rigidity of the checkboxes, the GSEs have kept commentary windows within each major section of the report, allowing appraisers to explain the non-traditional aspects of a property, though these are far more limited than the previously-used addenda. But this has generated widespread pushback from real estate appraisers who worry that the sheer volume of mandatory picklists and character-limited boxes will make it challenging to capture the subtle nuances of unusual, multigenerational, or one-of-a-kind homes.
If a home is unusual or unique, there may not be a pat field or combination of fields that adequately describe it. According to appraisal technology provider Reggora, approximately 94% of the data fields are new or restructured to align with Mortgage Industry Standards Maintenance Organization (MISMO 3.6) standards. Critics argue that forcing an unconventional layout or home type (like a converted historic barn, alleyway homes, or multigenerational properties with ADUs) into fixed data drops and tight validation rules may flag the property for automated collateral review errors.
The mandatory shift to the data-centric MISMO 3.6 architecture complicates valuations for multigenerational homes, alleyway properties, and one-of-a-kind structures in a number of ways.
Unique & One-of-a-Kind Washington DC Homes
In Washington DC, historic adaptively-reused structures or architectural gems hidden within historic preservation zones could experience issues with UAD 3.6 appraisals:
- Under the UAD specification, a Q1 rating is reserved for an “individually designed, one-of-a-kind structure” featuring rare craftsmanship. But, the moment an appraiser selects “Q1,” the system triggers stringent data requirements. The appraiser must individually define the specific high-end finishes of the exterior and interior independently. If a home has a globally unique architectural exterior but standard interior drywall, the automated validation rules struggle to reconcile the mismatch;
- Narrative Marginalization: While commentary boxes still exist, automated valuation models (AVMs) and appraisal review software read data fields, not stories. If the data fields look wildly irregular compared to the zip code average, the loan can get stuck in a manual review loop, resulting in the closing delays and higher appraisal fees currently observed during the UAD 3.6 rollout.
Washington DC’s version of “one-of-a-kind” architecture could create standard-defying issues for these specific property types:
- Alleyway Homes: DC is famous for its historic alley networks like Blagden Alley, Naylor Court, Brown’s Court, Bloomingdale Court, Hughes Mews, Snows Court and Pomander Walk. These alleys feature 19th-century brick carriage houses converted into luxury, ultra-modern single-family homes, early 20th century Victorian-style homes, compact one and two bedroom dwellings, and live-in artist spaces. These home types could struggle significantly under UAD 3.6’s automated risk-scoring mechanisms. The exterior is classified under strict historic preservation rules (often rough-hewn, century-old exposed brick, original carriage barn doors, and zero-lot-line placement), easily triggering a custom architectural flag. However, the interior could be a gutted, minimalist steel-and-glass open-concept loft with high-end European finishes. Under UAD 3.6’s strict rule that requires the appraiser to independently score and mathematically reconcile interior vs. exterior finishes, the automated underwriting engine flags this mismatch as a data anomaly. Perhaps even more problematic is input of comparables. To justify a valuation, the appraiser must input peer properties into the exact same standardized data buckets. Because alleyway homes are rare, finding local comps that match the same automated site-grid fields is incredibly difficult. When the appraiser uses standard street-fronting homes as comps and tries to apply manual adjustments, the automated system flags the appraisal for excessive variance. UAD 3.6 also demands rigid, standardized data regarding road types, easement access, and legal lot configurations. Alleyway homes often feature non-standard ingress/egress, shared private easements, or zero-lot-line setups. Forcing these nuanced property shapes into standardized MISMO data fields often triggers automatic “red flags” or review prompts in the lender’s loan origination software.
- Remodels of signature DC properties: Harry Wardman built thousands of classic front-porch rowhomes across DC neighborhoods like Petworth, Columbia Heights, and Woodley Park. Occasionally, someone reinvents one by retaining the front façade to satisfy the Historic Preservation Review Board, but enlarging the home on the rear with modern architecture and finishes. The property exists in a ZIP code where 99% of the homes are standard Wardman layouts. When the appraiser marks this home as a “Q1” due to its bespoke, architectural rear expansion and other modern features, the system demands unique, room-by-room material tracking. The automated system will look at the neighbor’s standard home, compare it to the automated valuation model (AVM) for that block, and reject the appraisal because the data parameters deviate too sharply from the neighborhood average.
- Mid-Century Modern Landmarks: Southwest D.C. features highly unique mid-century modern architecture, including modernist townhomes designed by famous architects like Charles Goodman. These homes feature floor-to-ceiling glass walls, flat roofs, and open floating floor plans. To standard appraisal software, a flat roof and massive panels of non-tempered historic glass look like a “condition or utility liability” rather than a premium architectural asset. Because UAD 3.6 forces the appraiser to use standardized dropdown menus to describe construction materials, the appraiser cannot easily check a box that says “historic architectural glass feature.” They are forced to select basic material categories, which strip away the aesthetic value of the architecture and reduce it to standard, flat data points that look unfavorable to an automated system. This is, in fact, a liability that would affect a great many Washington DC homes, which are valued as much due to their storied pasts and signature architecture as for more common attributes such as number of bedrooms and bathrooms, square footage and zip code.
- Multigenerational Homes & ADUs: UAD 3.6 significantly expands eligibility for Accessory Dwelling Units (ADUs), allowing lenders to count ADU rental income and support up to three ADUs on a single-family property. But the reporting logic triggers problems. It strictly separates Gross Living Area (GLA) from ADU space based on ANSI standards. For multigenerational homes where an “in-law suite” might be integrated via an interior door or stairway but has a dedicated kitchenette, appraisers face a data validation nightmare. If the appraiser classifies it as part of the primary GLA, automated underwriting systems (AUS) may flag it as a non-permitted second kitchen. If they classify it as an ADU, it is mathematically chopped out of the main home’s square footage, artificially deflating the primary structure’s size. And because UAD 3.6 relies on a mathematical formula; Interior Quality + Exterior Quality = Overall Rating with separate interior and exterior quality ratings which the appraiser must reconcile into an overall quality rating, every single room in a multi-unit or multi-suite setup requires individual material drop-downs. If a main house is highly upgraded (Q2) but the attached multigenerational wing or level utilizes builder-grade materials (Q4), reconciling a single “Absolute Quality Rating” (Q1–Q6) creates serious data friction during automated reviews.
When “Further Review” Becomes a Consumer Problem
A lender’s review message does not automatically mean an appraisal is wrong or the mortgage will be denied. But for a buyer working under a purchase contract, review is not a neutral event. It can cost time, jeopardize contingencies and rate locks.
Under the legacy system, appraisers could use narrative comments and addenda to explain why an unusual property required distant comparable sales, large adjustments or treatment that did not fit neatly within the form. With UAD 3.6, on the other hand, freeform appraiser commenting is highly confined to section-specific fields with fixed character limits. Supporting materials like legal descriptions, photos, and defect details are now permanently anchored to the specific data elements they support within a machine-readable, dynamic XML/ZIP format rather than attached as separate exhibits at the back of the report. A Facebook post in the group appraisalbuzz by appraiser Nora King of Nora King & Co. describes the issue, relating it to USPAP (Uniform Standards of Professional Appraisal Practice) documentation requirements.
This creates a potential problem for unusual homes. An appraiser may provide a sound explanation for comparing an alley-access house with street-fronting properties, for example, while the structured data still shows substantial differences. A collateral-review system may identify those differences for further examination even when the narrative explains them.
A review message is not a rejection. It may only prompt the lender to examine the report more closely. But it can also lead to questions, requests for clarification, appraisal revisions or additional supporting evidence. In some cases, the lender may decide that the report does not adequately support the value or that the property falls outside its risk tolerance.
For the buyer, the distinction between a warning and a rejection may offer little comfort while the clock is running. A manual review can delay mortgage approval even if the loan eventually closes. Those delays can affect:
- Deadline for an appraisal contingency
- Expiration of the buyer’s mortgage-rate lock
- Scheduled closing date.
The risk may be greatest for properties that already require more analysis, such as those outlined above. These homes can have fewer comparable sales and more characteristics that require explanation.
What homebuyers should ask
Before allowing a lender to order an appraisal, ask your lender:
- Will my appraisal use UAD 2.6 or UAD 3.6?
- What is the appraisal fee?
- Could the final fee be higher than the quoted fee? If so, why?
- What is the turnaround time for the new appraisal format?
- Could an appraisal delay affect my contingencies, closing date or rate lock?
- Is the property type one that could experience review issues?
- If an issue occurs, is the appraisal transportable to another lender?
Get the answers in writing when possible. If you are comparing mortgage offers, compare the total cost of each loan, not just the interest rate or appraisal fee. And don’t be shy about asking for discounts. Even if the lender’s policy prohibits discounting appraisals, other fees may be shaved to compensate for the increased appraisal cost.
When including financing and appraisal contingencies in an offer, keep the extended timeline in mind. Lender promises of a short turnaround time for appraisal should be met with skepticism. Not only will the new appraisal system take longer to produce reports, lenders’ underwriting departments must still review and accept them before releasing to borrowers.
Think carefully before switching lenders after an appraisal has been ordered. Few conventional loan appraisals are transportable, so changing lenders could mean paying for a second appraisal.
Sources
- Scotsman Guide: UAD 3.6 appraisal overhaul puts mortgage borrowers on the hook for higher costs Reporting on the approximately $550 versus $850 appraisal fees, possible three-to-five-day delays and comments from NAMB President Michael Farrell
- Fannie Mae: UAD Overview Official overview of the modernized Uniform Appraisal Dataset and redesigned Uniform Residential Appraisal Report
- Freddie Mac: Uniform Appraisal Dataset Overview Official explanation of the dynamic URAR, standardized data and transition away from multiple legacy forms
- Fannie Mae: UAD 3.6 Policy Update Official transition requirements, temporary policy exceptions and implementation dates
- Fannie Mae and Freddie Mac: UAD 3.6 Specification Technical documentation for the redesigned dataset, including property structures, levels, units, rooms, energy features, concessions and other report data
- National Mortgage Professional: New UAD 3.6 and Redesigned URAR Begin Limited Production Industry reporting on the launch schedule and early lender adoption
- Reggora: UAD 3.6 Mandate